
Market News
Global equities opened the week under pressure as the technology sell-off deepened. In Asia this morning, markets were generally lower – Nikkei 225 (-2.4%); Shanghai Composite (-0.9%); Kospi (-3.6%) – while the Nasdaq futures are currently down another 1%. This week, there are two events – NVIDIA’s results (tomorrow) and the Anthropic IPO (Thursday) – that may influence the near-term direction of equity markets. The ousted NVIDIA CEO Jensen Huang is reportedly in discussions about a potential comeback, while Treasury Secretary Scott Bessent is urging a “dramatic” leadership shake-up and greater transparency on export control compliance.
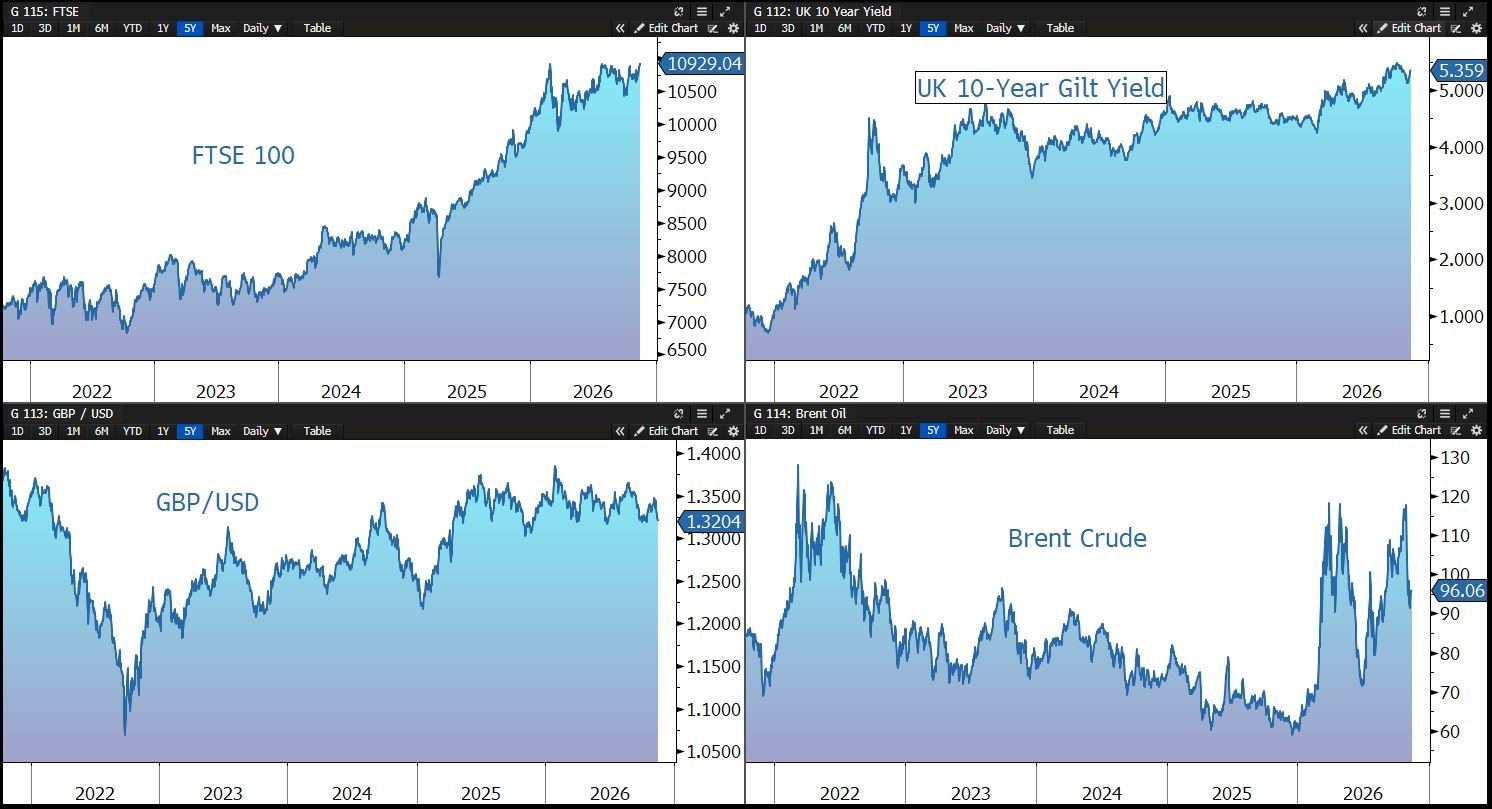
Brent crude is trading around $96 a barrel, after Iran struck a US helicopter base in Bahrain, marking its first attack on a Persian Gulf state in several weeks. Iranian state television also reported that five vessels had hit mines, while maritime authorities confirmed an attack on a tanker. However, price upside remains capped after the International Energy Agency reported last week that global oil supply had exceeded demand for the first time since the conflict began, projecting a surplus of 2m barrels per day this quarter as shipments through the Strait of Hormuz gradually recover.
Gold has weakened to $3,860, its lowest level in more than a year, as a stronger US dollar and elevated Treasury yields continue to pressure the precious metal. The move is being driven by growing expectations of a faster pace of monetary tightening by the US Federal Reserve. Markets are currently pricing in a 92% probability of a 25-basis-point rate increase next month, while the likelihood of a larger 50-basis-point hike stands at 8%. Investors are now looking ahead to remarks from Fed Chair Kevin Warsh later in the day for further insight into the central bank’s policy direction, as well as the release of the October FOMC meeting minutes on Wednesday. The yield on the 10-year US Treasury is currently 5.14%.
China’s October activity data disappointed across the board, with retail sales rising just 0.4% year-on-year versus a 0.8% consensus estimate, and fixed asset investment falling further than expected. The data reinforces doubts about the effectiveness of Beijing’s latest stimulus package and weighs on commodity-linked assets. Meanwhile, President Trump is attending an unprecedented three-way summit with Chinese President Xi Jinping and Russian President Vladimir Putin.
The FTSE 100 remains relatively resilient and is currently little changed this morning at 10,914. In an FT interview, Huw Pill, the Chief Economist at the Bank of England said “we will see evidence that motivates further (interest rate) rises” next year and that the Bank “will do what is necessary to get inflation back to 2%.” Inflation and jobs data due out later this week are seen as potentially hawkish catalysts. Sterling trades at $1.3215 and €1.1990, while the 10-year Gilt yields 5.35%.
Source: Bloomberg
