
Market News
Global equities are limping into the weekend as the fallout from Jensen Huang’s ousting at Nvidia continues to weigh on sentiment. Yesterday’s US session saw the S&P 500 (-0.4%) and Nasdaq (-0.4%) close lower, as a second consecutive Treasury sell-off, driven by accelerating Fed rate-hike bets, compounded the tech-led decline. Analysts have flagged increased uncertainty for the broader semiconductor complex, and the read-through to hyperscaler capex plans and AI infrastructure names will be closely watched.
The Nasdaq 100 futures are down 0.3% in early European hours. In Asia this morning, the main indices are mixed: Nikkei 225 (+0.5%); Hang Seng (-1.6%); Shanghai Composite (-0.6%); Kospi (-1.0%). The yen briefly weakened past 160 per dollar before rebounding on intervention speculation, prompting a warning from Japan’s Finance Minister.
The yield on the 10-year US Treasury is now 5.13%, while gold has dipped below $3,900 an ounce. The key data point today is US producer price inflation. Consensus expects headline PPI at +0.4% MoM and +6.6% YoY, following a hot +1.3% MoM reading last month. With multiple Fed officials – Daly, Williams, and Hammack – all reiterating the need for further tightening this week, a hotter-than-expected print could accelerate the Treasury sell-off and push yields even higher.
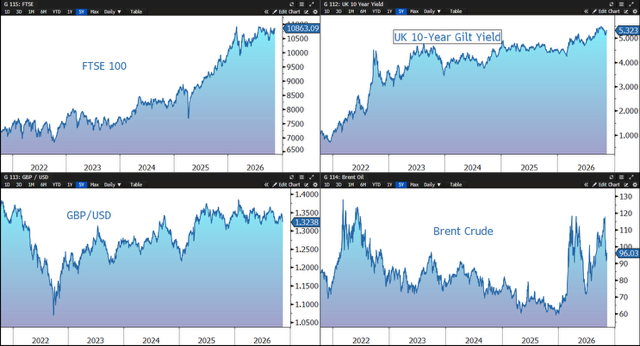
Brent crude moved up to $96 a barrel as President Trump stated that the US no longer needs a deal with Iran, dampening hopes for a diplomatic resolution to the war. Trump also directed Vice President JD Vance to prioritise domestic matters over negotiations with Tehran. Meanwhile, Iran maintained its position that Washington must lift its naval blockade and sanctions against the country before any direct peace talks can take place.
The US and China have officially extended their bilateral trade truce by two months to 10 January 2027, suspending retaliatory measures including China's additional 24% tariff on US goods.
The FTSE 100 is currently little changed at 10,863. Aviva is trading 2% higher following the release of strong general insurance premium growth, while DFS (-7%) warned upholstery market demand has softened further, driven by continued pressure on household budgets and reduced consumer confidence. Shares in Richemont are down 6% after the Cartier-owner reported a sharper-than-expected growth slowdown in its key Jewellery Maisons division, despite group sales beating consensus.
Microsoft’s severe outage affecting Outlook, Teams, and Copilot – with approximately 200,000 reports of disruption globally – is a significant operational risk for UK businesses and financial services firms entering the trading day.
Source: Bloomberg
