
Morning Note: Market News and an Update from Pernod Ricard.
Market News
A global equity market sell-off deepened as chip stocks plunged on Wall Street and in Asia, further unwinding this year’s blistering rally in the AI trade. South Korea’s Kospi Index — a bellwether for the AI trade — tumbled 7.6%, with chip heavyweights Samsung and SK Hynix both sinking. Elsewhere in Asia, the Nikkei 225 fell 4.9%. TSMC's Q3 results beat on profit (+69% net income to NT$763bn) and delivered a stronger-than-expected Q4 revenue outlook of up to $54.3bn. The Nasdaq is currently expected to open down 1% this afternoon.
US inflation for September came in hotter than expected. While higher energy prices were the main driver, the data also pointed to relatively broad-based inflationary pressures. Annual inflation accelerated to 3.7%, above forecasts of 3.6%, while the annual core inflation rate edged up to 2.6%, exceeding expectations of 2.5%. The initial response was a jump in Treasury yields, with the 10-year surging by nine basis points to 5.32%, approaching the highs last seen in early 2002. However, the flight to safety against a backdrop of slumping equity markets caused a sharp reversal overnight, with the 10-year now yielding below 5.10%. Gold has found favour and currently trades at $4,150 an ounce.
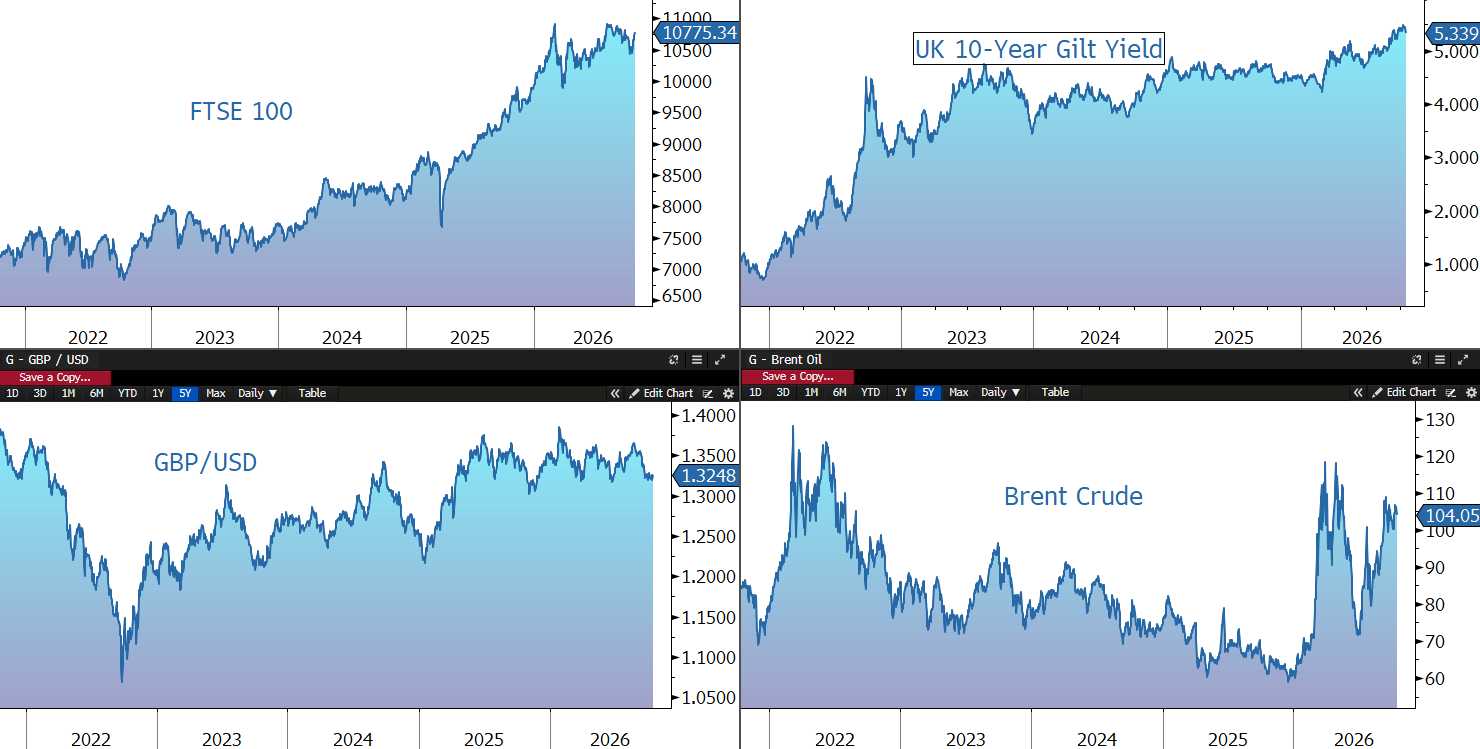
Brent crude fell back to $104 a barrel as investors assessed reports that the US is considering relaxing sanctions on so-called shadow fleet vessels that have transported oil and petroleum products from countries such as Russia, Iran, and Venezuela, as part of efforts to ease record-high global freight rates.
The FTSE 100 is currently 0.5% higher at 10,775. Companies trading ex-dividend this morning include Diageo (1.32% price impact), ITV (2.55%), Smiths Group (1.23%), Spirax Sarco (0.69%), and Tesco (0.98%). Sterling trades at $1.3245 and €1.1815, while the 10-year Gilt yields 5.34%.
Source: Bloomberg
Company News
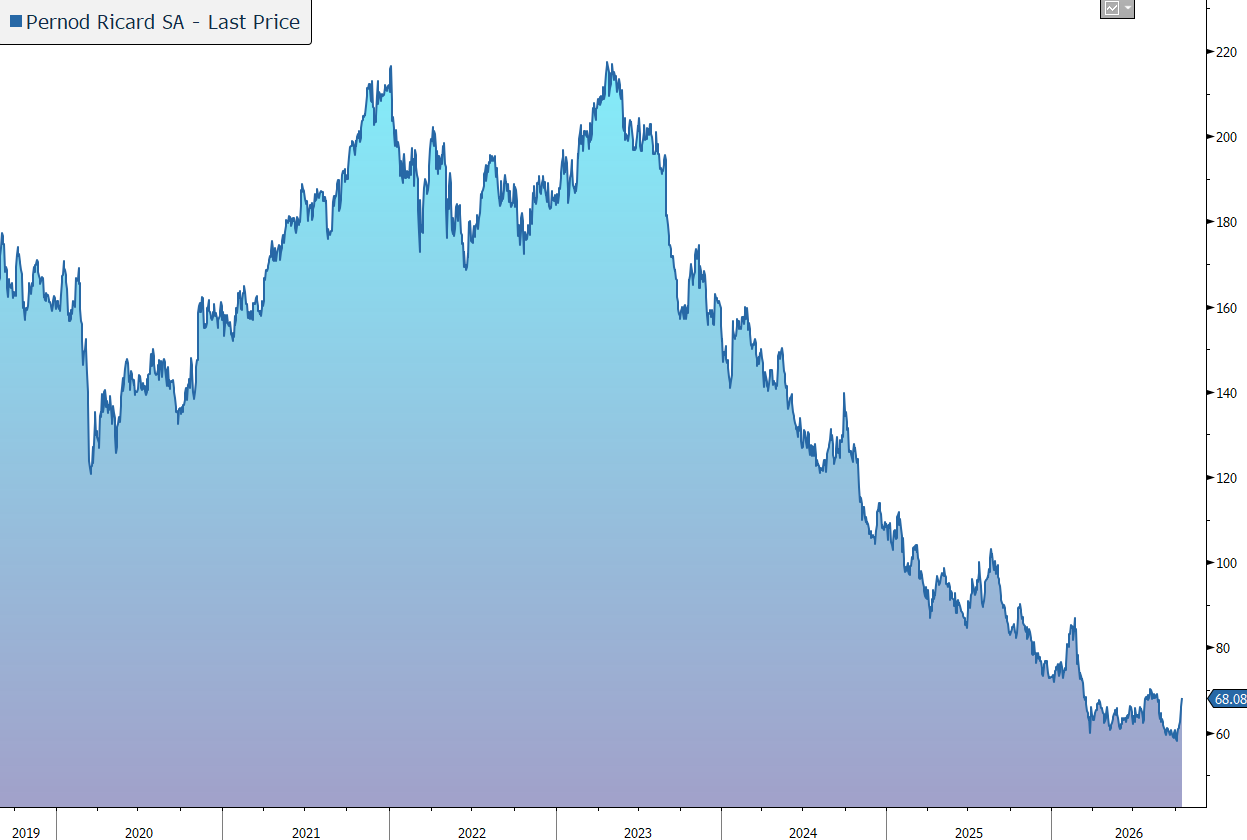
Pernod Ricard has released a sales update for the three months to 30 September 2026, the first quarter of the group’s financial year to 30 June 2027. The company enjoyed a sequential improvement versus the previous quarter, albeit organic sales are still down slightly in a tough macro-economic environment. In response, the shares are up by 3% in early trading.
Pernod Ricard is the No.2 worldwide producer of champagnes and spirits, operating a decentralised structure comprised of a global flagship in France, autonomous affiliates, brand companies, and market companies throughout the world. The company owns a portfolio of over 240 premium brands available in over 160 countries, including 17 of the Top 100 Spirits Brands. Key brands include Ricard, Pernod, Chivas Regal, Jameson, Glenlivet, Martell, Mumm, Perrier-Jouet, Absolut, Malibu, Beefeater, Havana Club, and Plymouth Gin.
The company is undertaking a €1bn Operational Efficiencies programme during FY2026-2029, which includes the rollout of its Fit for Future operating model. One third of the targeted efficiencies will be delivered this year and the company has accelerated the normalisation of its strategic investments.
The global environment remains volatile and uncertain, notably with ongoing conflicts in Europe and in the Middle East, and with cost-of-living pressures in some markets. Momentum and sales growth are improving in a number of key markets, demonstrating the benefit of a diversified premium brand portfolio.
In the three months to 30 September 2026, reported sales fell by 6.3% to €2,234m. Stripping out the impact of M&A and currency movements, sales fell by 0.9% organically, held back by declines in the US and China impacted by inventory adjustments. Elsewhere, growth was 4%, with strong performance notably in markets in the Asia-Rest of the World region and with softer results in Europe and in Latin America.
The result was a sequential improvement versus the previous quarter. Volumes returned to growth at 6%, with Strategic International Brand volumes growing by 2%.
The Americas suffered a 9% decline in organic sales. Within the mix, the US fell by 10%, amplified by some inventory adjustments, with spirits market conditions slightly improving over the summer. Canada declined modestly, while Mexico declined sharply due to continuing weak consumer demand and Brazil declined due to phasing.
Sales in China contracted sharply (-25%), with continued macroeconomic weakness that impacted consumer sentiment and demand, plus some inventory adjustments. Underlying depletions in China returned to growth, confirming the cautious trade optimism ahead of the Mid-Autumn Festival. India (+19% in organic terms) enjoyed strong underlying growth as the market continues to enjoy dynamic consumer fundamentals, and sales driven by strong demand and continuing premiumisation. The company is taking preparatory steps for a potential IPO of the India business which is leading to a favourable pipe-fill effect that further benefitted sales in Q1.
Europe (-6%) suffered a soft start to the year, impacted by phasing in some markets and continuing pressure in the on-trade.
Global Travel Retail sales were soft (-4%), impacted by the ongoing Middle East conflict, disproportionately affecting the Asian markets, while noting a strong Mid-Autumn Festival promotional program supporting Martell sales.
By brand category, Strategic International Brands fell by 1%, with strong momentum for Jameson, Ballantine’s, Malibu and Perrier-Jouët, and more modest growth on Chivas Regal and Royal Salute offset by declines on Absolut and Martell. Elsewhere, growth in Strategic Local Brands (+6%) was offset by a decline in Specialty Brands (-5%).
For the financial year to 30 June 2027 the group expects broadly stable organic net sales. This is made up of declines in the US and China, impacted by inventory adjustments, with underlying trends expected to improve in China. Continued positive momentum is expected in the Rest of World, with ongoing strong growth notably in India. The company confirmed it will strongly defend its organic operating margin to the fullest extent possible, supported by strict cost control and the €1bn operational efficiencies programme.
The company repeats that it remains confident in the attractive fundamentals of its industry, its strategy, and the resilience of its operating model to deliver sustainable value over time. Over the medium term (i.e. FY2027-FY2029), the company is projecting organic net sales growth, albeit at the lower end of its range of +3% to +6% p.a., and annual organic operating margin expansion.
Source: Bloomberg
