
Morning Note: A Round-up of Global Financial Market News.
Market News
US equity futures edged higher after Fed Chair Kevin Warsh declined to dispel expectations that the central bank would hold rates at its meeting later this month and predicted a surge in investment in the US. Warsh said at the IMF meeting in Bangkok that AI will be a huge benefit to the economy. Markets are currently pricing in approximately a 72% probability that the Fed will leave rates unchanged this month, while the likelihood of a rate hike in December has climbed to 92%. This followed a surge in US August PPI to 6.3%, more than triple the Fed’s 2% target and the second highest level in four years. The yield on the 10-year US Treasury is currently below 5.10%, while gold has moved up to $4,185 an ounce.
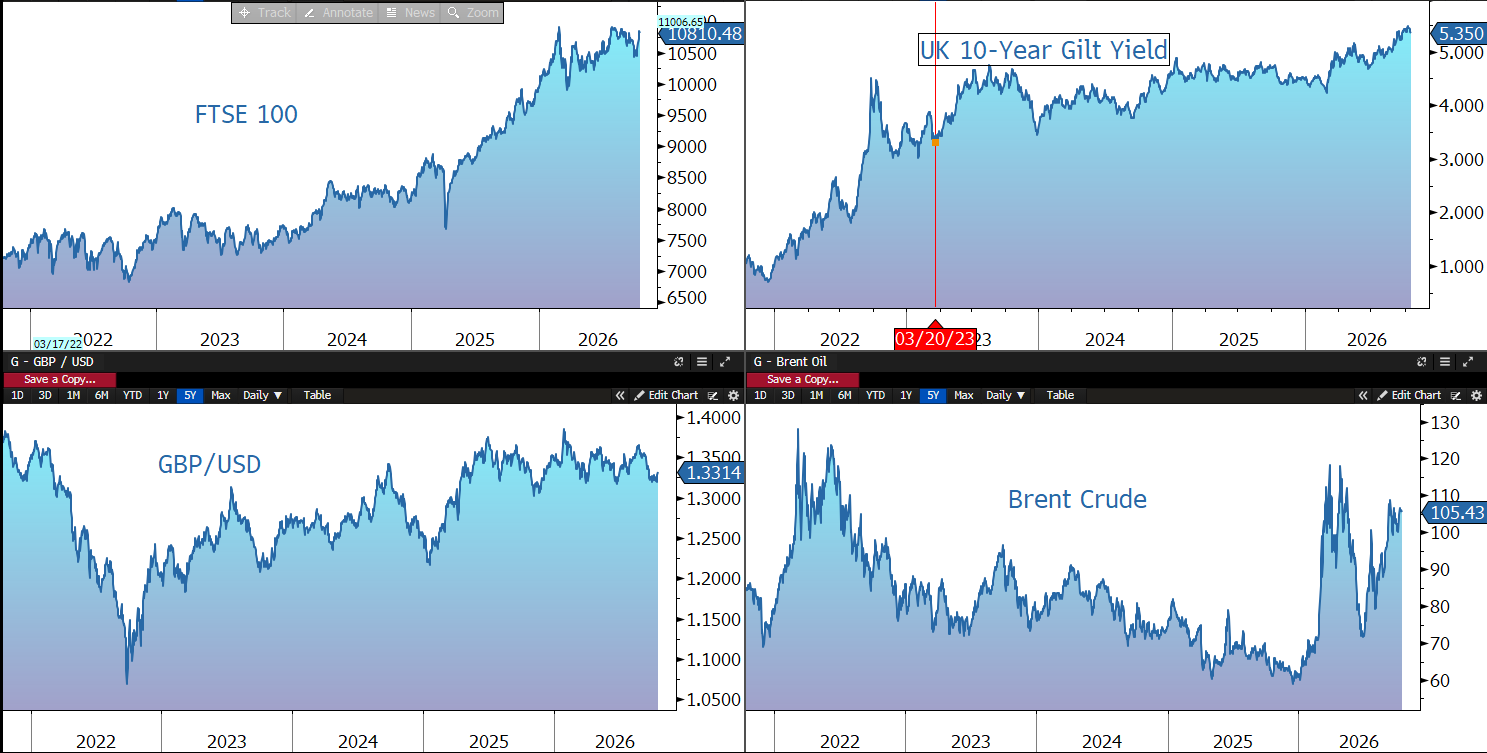
Brent crude trades at $105 a barrel. The IEA agreed to proceed with the release of the remaining 100m barrels of oil from a coordinated intervention launched in March, following lobbying efforts by US officials. Meanwhile, US diesel stockpiles remain tight, with 102.6m barrels of distillate on hand, according to the EIA.
In Asia this morning, equity markets recovered some of the previous session’s losses: Nikkei 225 (+1.4%); Hang Seng (+0.5%); Shanghai Composite (+0.2%); Kospi (+2.1%). However, Indonesian stocks plunged by the most in 28 years after MSCI warned it is considering downgrading the country.
CoreWeave’s credit risk climbed to a record as the AI data centre’s high-yield bonds extended declines. Three co-founders have sold $3.3bn in shares since the cloud computing company’s IPO.
The FTSE 100 is currently 0.3% lower at 10,810. The UK’s John Healey is set to raise taxes on banks, people familiar said, to fund cost-of-living support for voters and stabilise public finances. Sterling trades at $1.3315 and €1.1850, while the 10-year Gilt yield has drifted lower at 5.38%.
Source: Bloomberg
