
Morning Note: Market News and an Update from InterContinental Hotels.
Market News
Risk sentiment deteriorated sharply overnight as a split set of mega-cap tech earnings failed to sustain the prior session’s AI-driven rally. Tesla’s capex cut to $20bn (from $25bn+) raised doubts about the pace of AI and robotics investment, while Meta’s record Q3 revenue of $64.6bn and raised capex guidance to $135bn–$145bn for the year, sending a conflicting signal.
Nasdaq 100 and S&P 500 futures are currently down 1.6% and 0.9% respectively, reversing last night’s gains. Asian equities sold off broadly this morning: Nikkei 225 (-2.7%); Hang Seng (-3.2%); Shanghai Composite (-1.5%); Kospi (-3.5%).
Escalating Middle East hostilities drove Brent crude above $111 a barrel, after Houthi drone strikes on Saudi Aramco’s Shaybah field and King Fahd International Airport in Dammam killed three people. The US ordered non-emergency diplomatic staff to depart Saudi Arabia. The oil majors, such as BP and Shell, continue to hit new 10-year highs.
Treasuries rallied on safe haven demand, with the 10-year yield falling back to 5.08%. The yen strengthened to 157 versus the dollar. Gold fell to $4,100 an ounce as higher oil stoked inflation fears ahead of next week’s Federal Reserve meeting.
France’s 10-year OAT yield surged above 5%, reaching a new 24-year high as investors grew increasingly concerned about the country’s fragile public finances and mounting social unrest. The spread over 10-year German Bunds widened to around 160 basis points, its highest level since the eurozone sovereign debt crisis.
The FTSE 100 is currently 0.7% lower at 10,682, with results from Barclays, IHG (see below), Relx, and LSE seeing a mixed reaction. Companies trading ex-dividend this morning include BAE Systems (0.77% price impact) and Games Workshop (0.42%). Sterling trades at $1.3405 and €1.1920, while the 10-year Gilt yields 5.39%.
Nestle reported solid nine-month real internal growth of 1.9%, the best performance since 2021, with broad-based improvement across divisions and regions. The shares rose 2%.
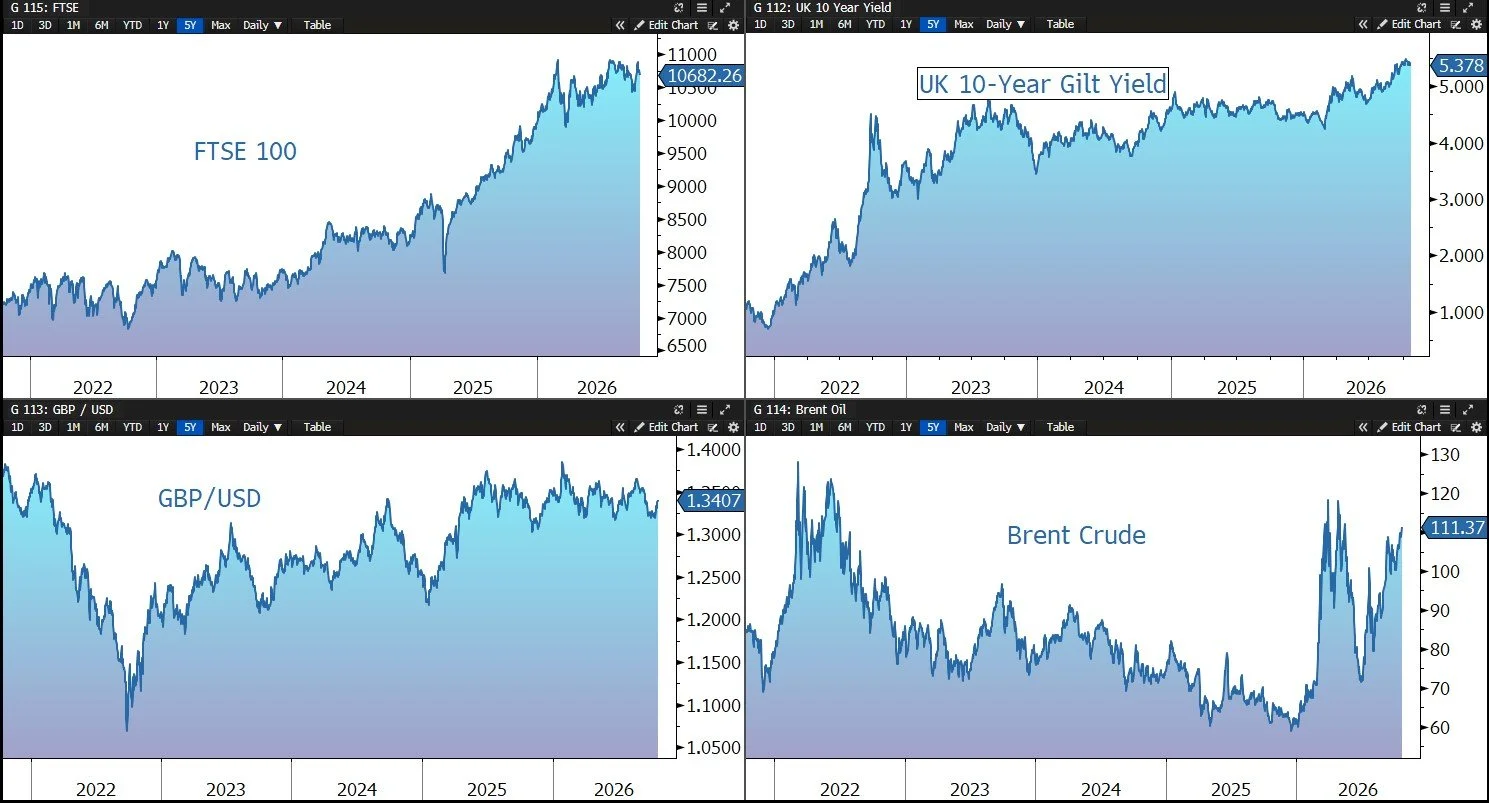
Source: Bloomberg
Company News
InterContinental Hotels Group (IHG) has released Q3 2026 results, which highlighted an acceleration in global trading as strong growth in the US offset weakness in China. Room growth momentum has continued, with underlying signings and openings ahead of last year. Despite ongoing geopolitical headwinds, the company remains on track to meet full-year consensus profit and earnings expectations. Ahead of the analysts’ meeting later this morning, the shares are down 2% against a weak overall stock market backdrop.
IHG owns a portfolio of 21 attractive brands across all price tiers (including Crowne Plaza, InterContinental, Holiday Inn, and Six Senses) and has a strong operating system, both of which drive customer loyalty and pricing power. The group operates a highly scalable, asset-light model, based on franchising and management contracts, with low capital intensity and high returns. The model also means the group doesn’t own hotels or bear the operational costs of running them. The company is focused on delivering industry-leading net rooms growth over the medium term. It currently has a 4% global market share and a 10% share of the new room pipeline. At the end of September 2026, the global estate was more than a million rooms across 7,186 hotels, with 65% in midscale segments and 35% in upscale and luxury. Annual gross revenue generated by the group’s hotels is more than $35bn.
Long-term growth is being driven by a rising global middle class with a desire to travel – Oxford Economics forecasts this cohort to nearly double in size to over 670m households by 2035, with China accounting for almost half of the growth. Global leading hotel brands are expected to continue the long-term trend of taking market share. In periods when developers are adding less new supply, revenue growth from existing room inventory is expected to be stronger, as are conversion opportunities, which IHG has proven highly successful at capturing.
IHG’s approach to AI is grouped into three areas: guest acquisition using a fully AI compatible hotel content platform with enhanced search, trip planning, content and personalisation; improved hotel revenue generation; and improved cost efficiency using a new CRM system.
The group’s medium- to long-term financial framework targets:
· high single-digit growth (i.e. 7%-9%) in fee revenue, through a combination of growth in RevPAR (revenue per available room, the key measure of industry performance), system size, and ancillary revenue. In addition, the company expects 100-150 basis points of fee margin expansion annually on average. This excludes the positive margin impact of the credit card business.
· 100% conversion of adjusted earnings into adjusted free cash flow, supporting investment in the business to optimise growth, sustainably growing the ordinary dividend and returning surplus capital.
· 12-15% adjusted EPS compound annual growth rate, including the assumption of ongoing share buybacks.
From the start of 2026, the trading currency of the group’s shares on the LSE changed from Sterling to US dollars. The move does not affect the nominal currency of the shares which remains in Sterling, nor does it impact IHG’s London listing or its New York ADR listing. Shareholders based in the UK will continue to receive dividend payments in Sterling. The company’s aim is to better align its share price with its financial performance – the company already reports its results in US dollars – and simplify investment appraisal.
In the third quarter of 2026, the company delivered an acceleration in growth as its breadth by geography, brands, and stay occasions captured increasing guest demand around the world
Global revenue per available room (RevPAR) grew by 5.3%, ahead of the market expectation of 4.5% and an acceleration versus the 4.1% generated in the first half. This leaves year-to-date growth up 4.6%. Growth in occupancy – up 0.9 percentage points – was supplemented by an increase in pricing, with average daily rate up 3.9%.
By sector, global rooms revenue on a comparable basis was strongest in Groups (+10%) and Leisure (+5%), with Business (+4%) lagging.
By region:
· In Americas (the group’s largest division), RevPAR accelerated to +6.8%. The US (+6.9%) benefitted from the ongoing strength and breadth of the domestic economy and the final stages of the FIFA World Cup in July, together with IHG’s enterprise platform.
· The diverse EMEAA region grew by 5.0%, representing a significant improvement on the 0.6% growth rate of the prior quarter. Growth was driven most notably by East Asia & Pacific, which included an increase in inbound travel from China. Middle East, a sub-region which represents 19% of EMEAA’s system size but just 5% of IHG globally, was broadly flat in the quarter. We note the majority is in Saudi Arabia which has a big domestic market. In terms of the Middle East pipeline, 90% is in ‘safer’ countries: Egypt, Turkey, and Saudi Arabia.
· Greater China RevPAR fell by 3.3%, driven by adverse weather and changes to public holiday timings. RevPAR declined by 7.5% in Tier 2-4 cities, though in Tier 1 cities it grew by 0.2%.
IHG continued to open new hotels and sign more rooms into its pipeline as owner demand for its world class brands continues to increase. In Q3 2026, 12.9k rooms across 92 hotels were opened.
Gross system growth was 6.3% year-on-year, while after removals, net system size growth was 4.9% year-on-year (and 3.3% YTD). Demand for quick-to-market conversions to IHG’s brands continues to be high, representing 43% of openings and half of signings in the quarter. This is a big positive given the time to open is much shorter than with a new build. Note that accelerating system growth is creating near-term fee drag as hotels ramp up over 1-3 years.
IHG signed 21.1k rooms (164 hotels) in Q3. This leaves a global pipeline of 353k rooms (2,426 hotels), up 3.2% year-on-year, and 33% of the current system size, providing good growth visibility. Around 50% of the global pipeline is under construction.
As usual at this stage of the year, the group doesn’t provide an update on profitability or its financial position. The asset-light model means IHG has low investment requirements and a negative working capital cycle. The group operates a conservatively leveraged business model and maintains strong liquidity. At the end of the first half, financial gearing was 2.63x net debt to EBITDA, in the middle of its 2.5x-3.0x target range. It is expected to remain within the range at the year-end.
An update on the group’s recent bond activity was provided, and the group disclosed that after currency swaps, it now has a total of $4.6bn bonds outstanding, with a blended borrowing cost of approximately 5.1%. The company also confirmed that its expected range for adjusted interest expense for 2026 is $230m-$240m, while its preliminary view for 2027 is an increase of $40m-$60m.
The group is returning surplus capital through share buybacks. The current $950m programme is expected to be completed by the end of 2026, with $707m repurchased to date. Including the dividend, the company expects to return more than $1.2bn to shareholders in 2026, amounting to 5% of the current market cap.
Looking ahead, the company is confident of achieving full-year consensus profit expectations (i.e. EBIT of $1,399m) and adjusted EPS around the top end of its growth algorithm target of 12%-15% annually on average over the medium to long term. This is driven by the strength of IHG’s enterprise platform and its ability to further capitalise on its scale, leading positions and the attractive long-term demand drivers for its markets.
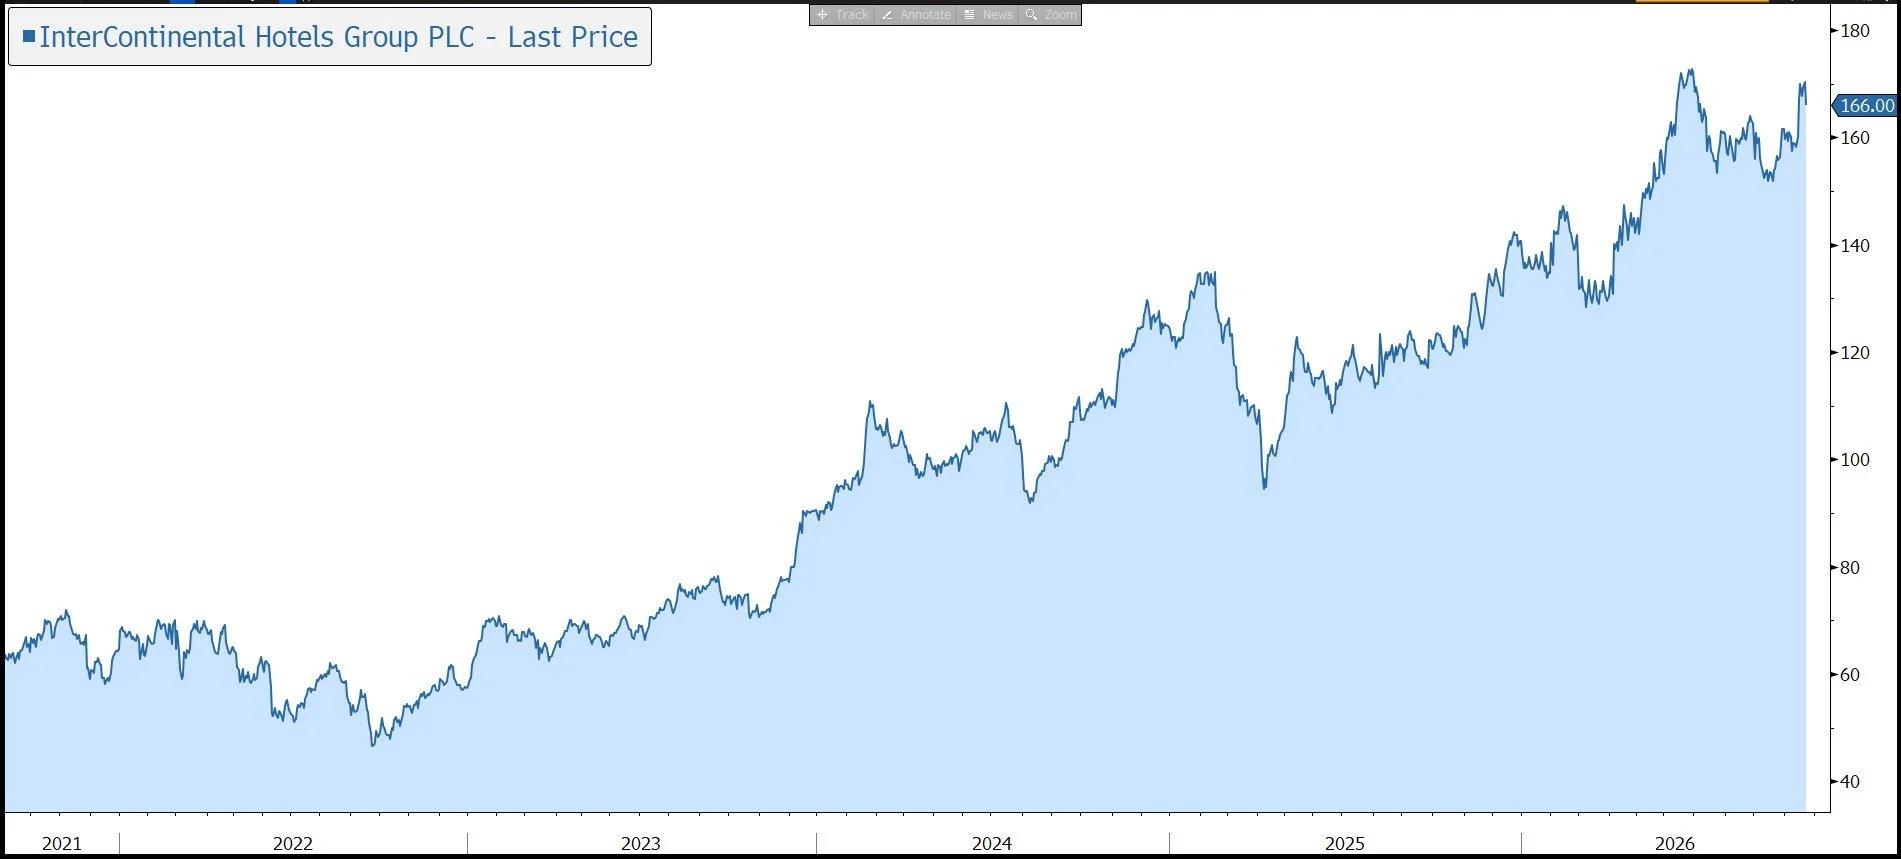
Source: Bloomberg
