
Morning Note: A Round-up of Global Financial Market News.
Market News
Equity markets kicked off the week on a sour note after Anthropic’s Dario Amodei called for a slowdown in the development of AI technology, a move backed by Elon Musk and Sam Altman. This raised concerns about a sector that has powered this year’s rally. Markets must now price whether this represents a genuine capex deceleration for hyperscalers and chip suppliers, or a temporary safety-driven pause with limited long-term impact on infrastructure spending. OpenAI’s Chief Executive Officer Sam Altman said that the company won’t go public this year.
In Asia this morning, the Kospi Index — a barometer of AI investment — fell 3.4%, while other markets in the region were also soft: Nikkei 225 (-0.7%); Shanghai Composite (-0.2%). Nasdaq 100 Index futures declined, with the market currently expected to fall 1.4% at the open this afternoon.
Brent crude jumped to $107 a barrel after Saudi Arabia shut a major crude pipeline because of attacks, while Oman said a planned meeting between Iran and Gulf states on a temporary shipping lane through the Strait of Hormuz was postponed. Brent has surged approximately 20% over the past two weeks.
The dollar strengthened and the yield on the US 10-year Treasury note stood around 4.96%, remaining near its highest levels since October 2023. That came after hotter-than-expected US inflation strengthened the case for higher interest rates. Swap traders now see a nearly 90% chance the Federal Reserve will raise its key rate on Wednesday, with Chair Kevin Warsh’s post-decision commentary likely to be scrutinised for the pace of any subsequent tightening cycle. Meanwhile, the Treasury Department’s latest buyback operation disappointed markets, with the US government repurchasing $5.2bn in bonds, below the $6.0bn maximum and roughly half of the $10.5bn offered in the operation. Gold slipped to $4,325 an ounce.
The FTSE 100 is currently bucking the trend, up 0.5% at 10,711, supported by the oil majors and other dollar earners. The monetary policy committee is expected to hold rates at 3.75% this week despite conflict in the Gulf, higher energy prices, and a sharp rise in gilt yields – the 10-year currently yields 5.37%, a 19 year high. The MPC is also expected to announce a slower pace of quantitative tightening for the year ahead. Sterling trades at $1.3495 and €1.1675.
President Trump expressed optimism about resolving his trade spat with Ottawa and downplayed the prospect of leaving the USMCA. A deal with Canada may come “fairly soon”.
Copper futures fell to around $6.40 a pound, extending last week’s losses to hit six-week lows. Last Thursday, the price plunged nearly 5% following reports that the Trump administration had delayed a decision on tariffs for refined copper imports.
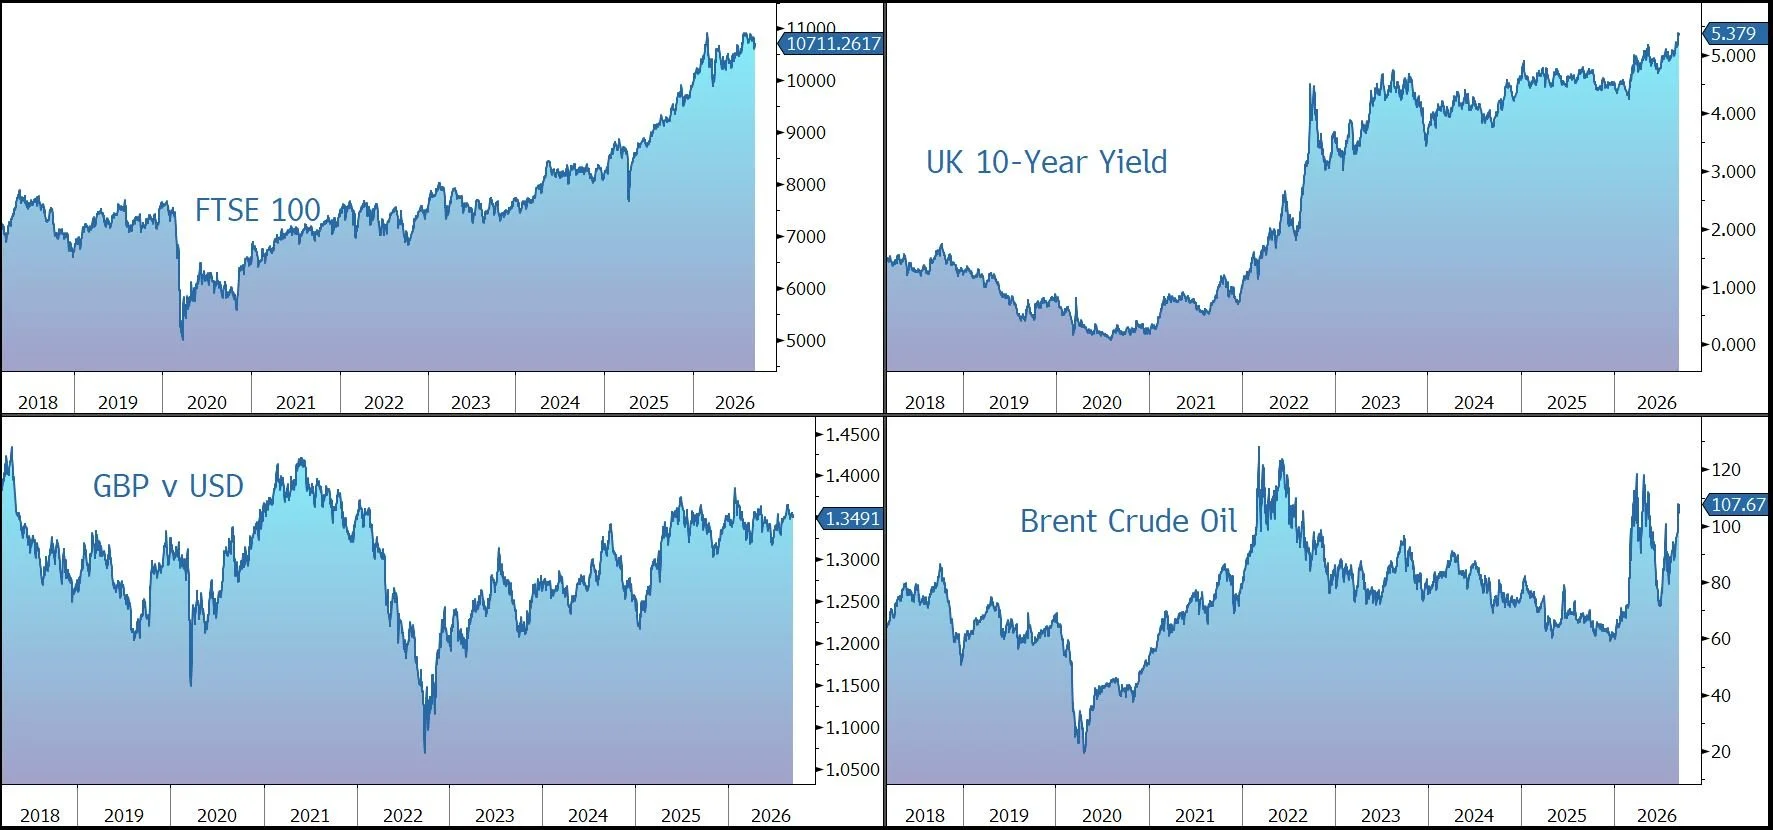
Source: Bloomberg
