
Market News
Pressure on AI-related stocks eased this morning following Friday’s sharp sell-off where the Nasdaq 100 Index slumped 3.5% – its worst day since June – and the Philadelphia Semiconductor Index plunged 7.2%. In Asia this morning, most benchmarks stabilised, with South Korea's Kospi reversing a 2% opening loss to trade 2.2% higher, supported by SK Hynix's buyback announcement and local fund buying. Other moves included: Nikkei 225 (-0.3%); Hang Seng (+0.4%); Shanghai Composite (+1.1%). At present, the US futures market is pointing a small gains at the open this afternoon.
The US data calendar today is consequential – ISM Manufacturing, ISM Prices Paid, and S&P Global US Manufacturing PMI are all due this afternoon. With the Federal Reserve still on a hiking path and inflation elevated, a hot ISM Prices Paid print could reignite interest rate fears and pressure both bonds and equities. Gold prices have climbed back above $3,900 an ounce, recovering modestly from one-year lows, while the yield on the 10-year US Treasury is currently 4.93%.
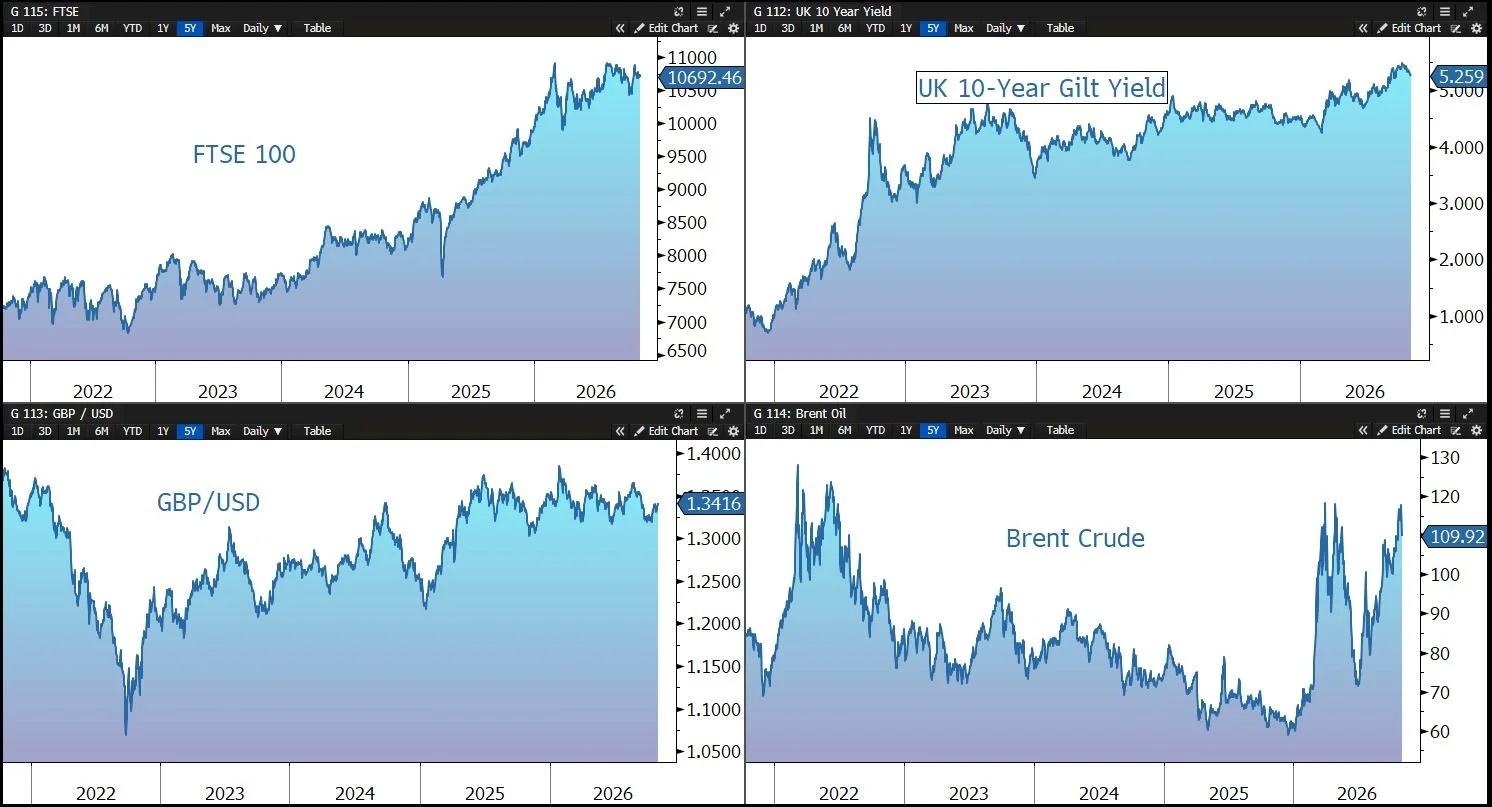
Brent crude is down more than 3% to below $109 a barrel, erasing gains from last week as investors weighed signs of diplomatic efforts to end the Middle East conflict against fears of renewed US military action against Iran. Reports indicated that President Donald Trump intends to allow diplomacy more time before deciding whether to resume strikes against Iran following the Midterm Elections (see below). Meanwhile, Qatari and Iranian officials continued negotiations for a third consecutive day, as Gulf countries try to prevent an escalation in the region. Separately, OPEC+ agreed over the weekend to keep its existing production targets unchanged through December as the group continues to monitor global oil supply and demand conditions.
The US Midterm Elections are tomorrow, with the Democrats seeking to wrest control from Republicans. The outcome will have direct implications for fiscal policy, tariffs, and equity markets. White House economic adviser Kevin Hassett said the administration hopes to work with whoever wins, but Trump has signalled he will not sign bills reversing key policies.
The FTSE 100 is currently 0.4% lower at 10,692. BP has completed the sale of a 65% stake in Castrol to Stonepeak for $6bn. As expected, the company will retain a 35% stake and use the proceeds to reduce financial obligations. The Bank of England is expected to raise rates on Thursday to contain the pick-up in inflation. Sterling trades at $1.3425 and €1.1975, while the 10-year Gilt yields 5.24%.
Alstom is down 25% this morning after cutting its full-year margin forecast and guiding to negative free cash flow of €1.5bn, citing delays and penalties on German rail projects. The company plans to slash debt by a further €2bn and is considering making divestments. This is the second profit warning this year.
Profit after tax at Ryanair fell 15% in the first half as unhedged fuel prices doubled to $130 a barrel. The company launched a cost-cutting programme to offset a €2bn fuel cost increase next year and the CEO warned profitability will take a hit.
Source: Bloomberg
