
Market News
Global equities are under broad pressure as a second consecutive session of tech-driven selling accelerated a rotation out of AI-linked names into haven assets. Nasdaq 100 futures slid as much as 2.3% overnight after Amazon fell 7% and Intel plunged 23% in after-hours trading on disappointing earnings and elevated capex concerns. The malaise continued in Asia this morning: Nikkei 225 (-2.1%); Shanghai Composite (-1.4%); Kospi (-3.5%).
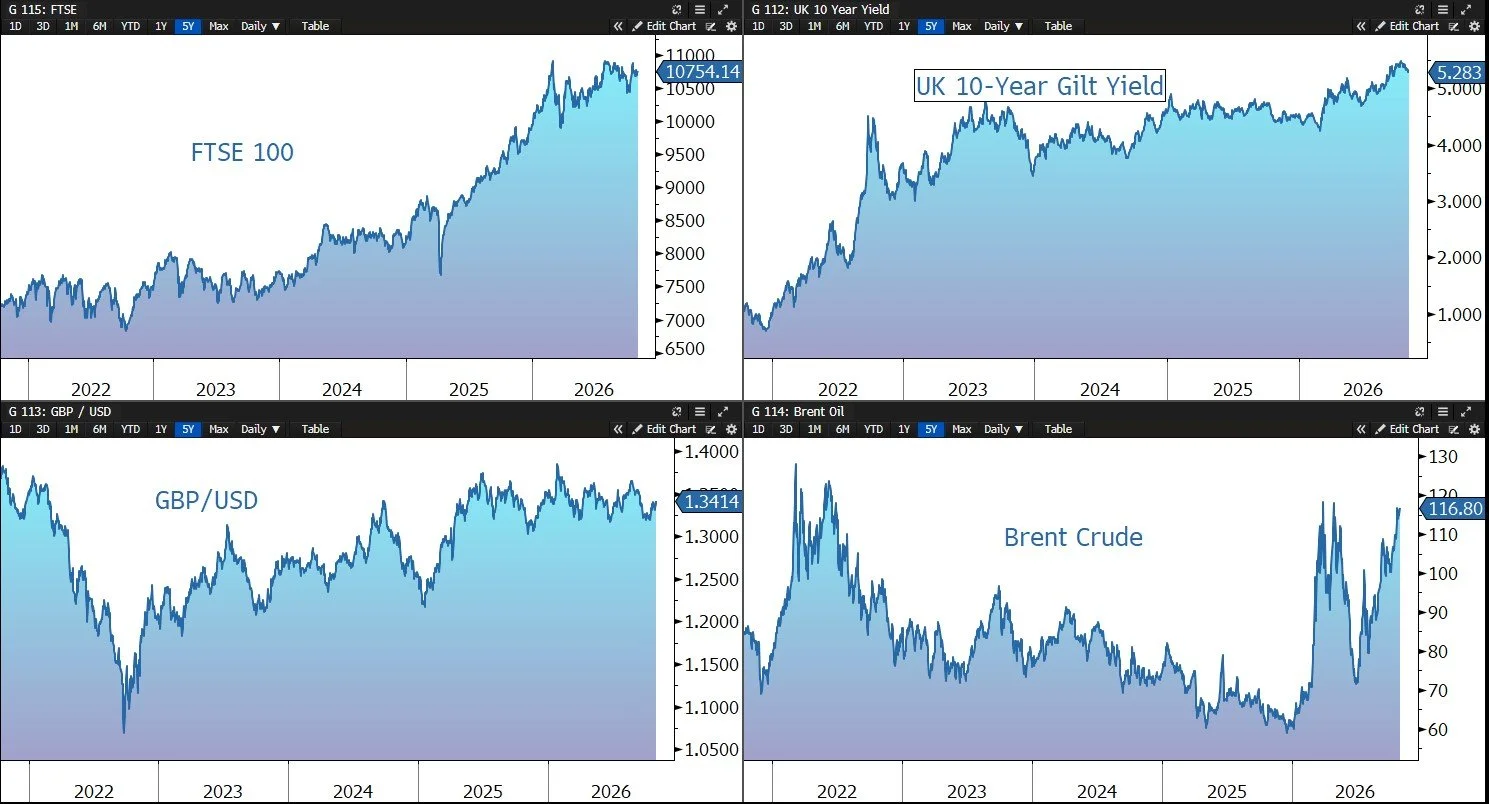
The FTSE 100 is proving to be something of a haven – it is currently up 0.5% at 10,754 – supported by the oil majors, such as BP which released strong Q3 results (see below) and AstraZeneca, which also reported good results. Other defensive, overseas earners, such as Unilever, Diageo, and Experian are also firm.
Treasuries are also rallying on haven demand, with the US 10-year yield at 4.93%. However, gold declined below $4,000 per ounce, extending losses from the previous session as persistent inflation and resilient economic growth in the US reinforced expectations of a potential Federal Reserve rate hike later this year.
Brent crude trades at $116 a barrel, supported by Middle East supply concerns, though gains are being pared on reports of renewed US-Iran diplomatic contacts via Qatari mediators.
The Bank of Japan held rates at 1.25% and declared for the first time that underlying inflation has reached its 2% target. Governor Ueda confirmed the bank will keep raising rates in response to economic and price developments, though he stopped short of signalling December timing, leaving the yen volatile and carry trades exposed.
Source: Bloomberg
Company News
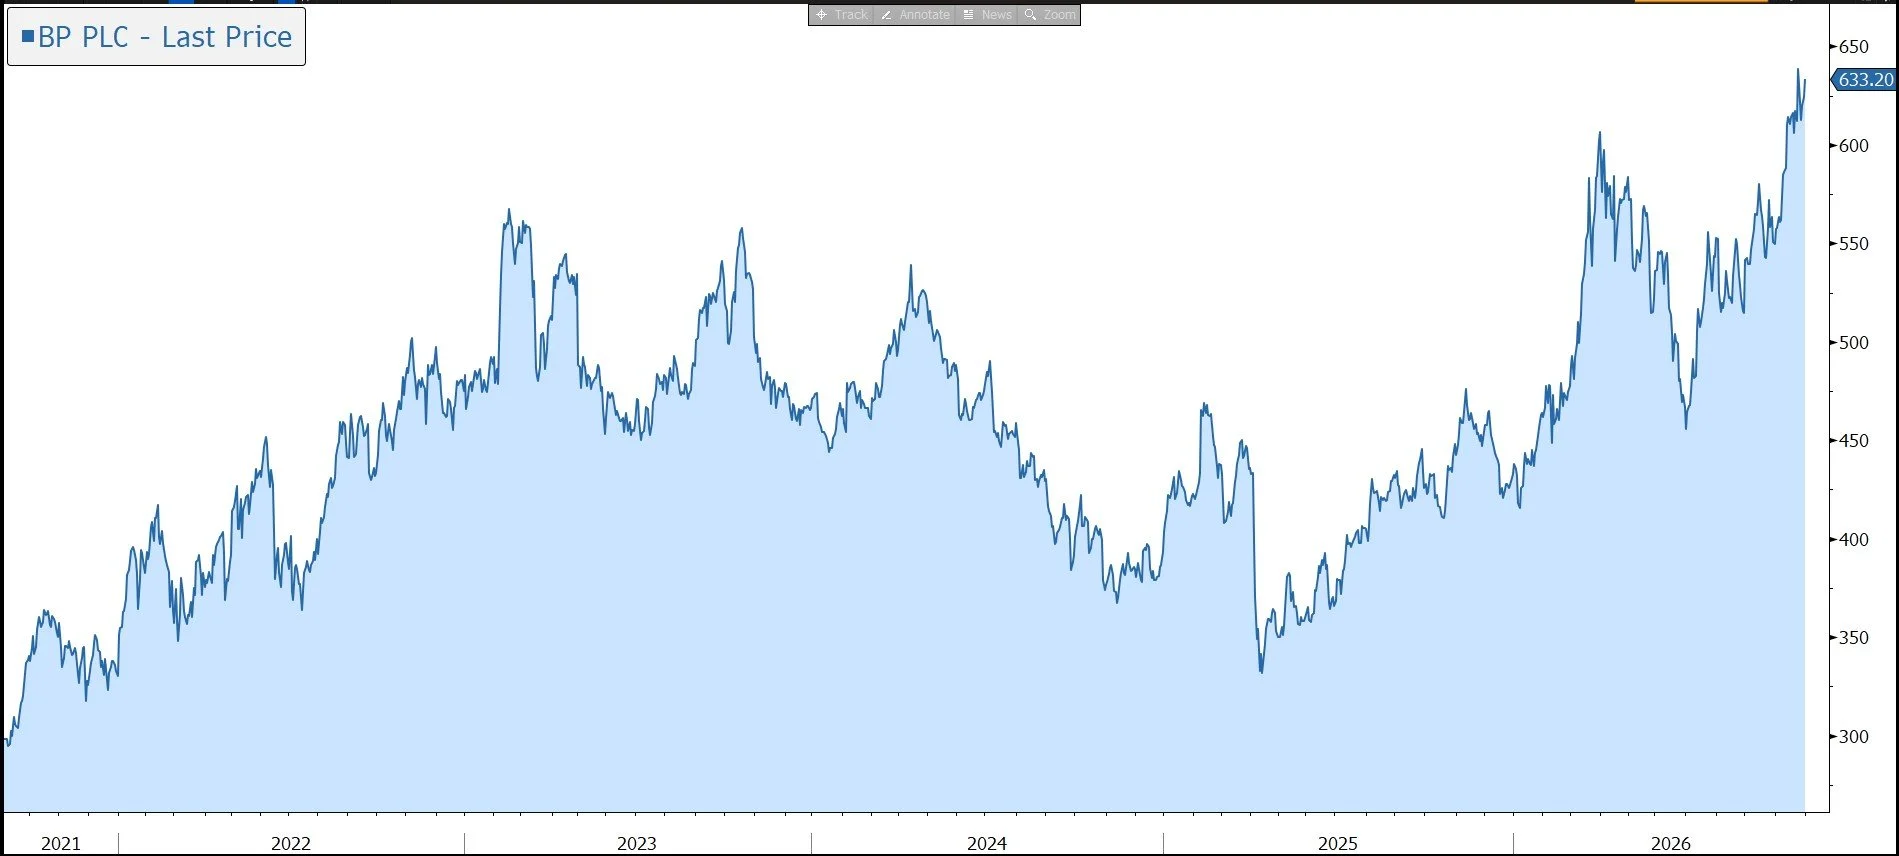
BP has today released Q3 results which were well above market expectations and the quarterly dividend was raised by 4%. The company has now delivered its net debt and structural cost reductions targets and has line of sight on the remaining two of the four primary financial targets the company set for itself for 2027. The focus will now move on to the December Strategy Day where the new CEO will set out the next phase of her plans to build a ‘simpler, stronger, and more valuable BP’. The shares have been strong this year and are up a further 2% in early trading this morning.
BP is a global integrated energy company with operations and assets across traditional hydrocarbon businesses (oil and gas exploration and production, refining, and retail), as well as select investments in renewable energy (e.g., Archaea biogas, EV charging, offshore wind). Embedded within its core businesses is a world class oil, gas, and power trading operation.
BPX Energy comprises BP’s onshore oil & gas shale operations within the Lower-48 in the US, primarily focusing on developing unconventional resources in Texas and Louisiana across three plays (Permian, Eagle Ford, Haynesville). Elsewhere, the company owns exploration & production assets in Trinidad, Egypt, the US Gulf, Libya, Indonesia, Namibia, Azerbaijan, Oman, the North Sea, and Brazil.
Following a period of corporate governance chaos, which saw two CEOs and a Chairman leave the company, BP has hopefully entered a period of certainty. New CEO Meg O’Neill – the first outsider to lead BP – is continuing the strategic reset, reorganising the group into simpler upstream and downstream units to drive efficiency. In September, Ian Tyler assumed the role of Chairman. Stability of management is important but also sustained operational execution.
The company has set out five priorities to deliver a step change in performance and grow shareholder value:
· Strengthen the balance sheet to provide the financial resilience needed to generate greater flexibility to invest to grow through the cycle and reward shareholders.
· Simplify the portfolio based on value, not sentiment and history. The group will focus on the assets with the strongest potential to deliver competitive returns and long-term value. Given the pool of potential organic growth opportunities, there are no plans for major acquisitions. That said, we note reports in late September of BP’s interest in Devon Energy’s Eagle Ford shale assets. However, the portfolio was formally sold to Crescent Energy for $4.2bn in early October. Although the assets would have been a good fit, the timing is probably a bit early in the group’s deleveraging cycle. It is unclear whether BP was outbid or exercised capital discipline.
· Invest with greater discipline to ensure every dollar of capital competes. The company will use balanced investment criteria to make decisions rooted in profitability, cash generation, and market realities. The company will compete in the ‘weight class’ it is in.
· Drive operational excellence. Although the company has made progress on reducing structural costs, it has not improved enough where it matters most: the bottom line. The company will move faster and has the opportunity and technology to do so. The target is $6.5bn-$7.5bn of structural cost savings by 2027, of which $3.5bn has been achieved. Portfolio actions, including the disposal of Castrol, should contribute around $1.5bn of cost base reduction. The majority of the organisational simplification benefits should start to materially flow through to earnings during 2027.
· Hard wire high-performance and accountability into BP – making better, faster decisions, reducing complexity, and sharpening accountability.
During the latest quarter, the company continued to simplify its portfolio. In the quarter, the Austrian mobility and convenience business was sold, the sale of the Gelsenkirchen refinery was completed, and plans were announced to market the North Sea and Archaea businesses. Still to come is the expected imminent closure of the Castrol divestment, unlocking $6bn of proceeds, following which BP will continue to own 35% of the business under a two-year lock-up. Finally, the divestment process for its solar business Lightsource BP to a Kuwait-backed group is underway.
Back to today’s update which highlights the continued impact of conflict in the Middle East. Heightened volatility in crude oil, natural gas, and refined products prices have impacted financial results, including trading results and working capital movements.
In the three months to 30 September 2026, underlying replacement cost profit – the key measure of the group’s performance – rose from $2.21bn to $8.46bn, well above the market forecast of $7.33bn. The result was driven by the higher-price, higher-margin environment and some good progress on performance improvement across the business. Compared with the previous quarter, underlying profit jumped by 48%, mainly reflecting significantly higher realised refining margins and a significantly higher gas and marketing trading result.
The commodity price backdrop was mixed: Brent crude averaged $96.99/barrel (down from $103.85/barrel in the previous quarter); US gas Henry Hub averaged $2.96/mmBtu (vs. $2.90/mmBtu); and the refining margin averaged $46.70/barrel (vs. $29.6/barrel). The environment has been volatile as a result of ongoing geopolitical uncertainty and the company believes that even when the conflict ends it will take months for the oil and gas supply/demand balance to normalise.
As a rule of thumb, the company has disclosed that: a $1 movement in Brent has a $340m profit impact, a $0.1 movement in Henry Hub has a $40m profit impact, and a $1 movement in the refining margin has a $450m profit impact.
The Q3 results include post-tax adjusting items relating to asset impairments of $4.0bn, primarily attributable to transition businesses in the gas & low carbon energy segment and are excluded from underlying replacement cost profit.
By division, the results for the quarter for underlying operating profit were: gas & low carbon energy (+110% vs. Q3 2025); oil production & operations (+54%); and customers & products (+305%). Reported upstream production in the third quarter was 2,200 mboe/d, in line with the previous quarter. Q4 production is expected to be between 2,090 and 2,230 mboe/d.
Cost discipline was strong, with overall unit production costs only up 6% year on year. Operational performance improved compared to the previous quarter – upstream plant reliability was 95.3%, while refining availability was 96.5%.
Despite higher oil prices, investment discipline remains a key priority. Capital expenditure was $3.0bn in Q3 and the company reiterated its full-year guidance to $13.5bn-$14.0bn.
Operating cash flow rose from $7.8bn to a stellar $14.8bn, including an adjusted working capital release of $0.5bn. Q3 disposal proceeds were $21m. In 2026, proceeds of $8bn are expected including $6bn from the announced Castrol transaction.
The company’s first capital allocation priority is a resilient dividend, which is expected to increase by at least 4% per ordinary share a year. Today, the group has declared a quarterly dividend of 8.66 US cents, 4.1% higher than last year, implying a full-year yield of 4.2%.
BP remains committed to maintaining a strong investment grade credit rating and a reduction in net debt. Progress has been excellent – in the third quarter, net debt fell from $22.3bn to $13.9bn, more than achieving the target $14bn–$18bn range a quarter early.
However, the net debt figure doesn’t include other financial obligations and instruments such as lease liabilities ($13.3bn), Gulf of Mexico oil spill payables ($5.1bn), and hybrid bonds (£12.1bn). In response, the company is planning to reduce hybrids by $4.3bn by end 2027, with $1.0bn of perpetual hybrid securities redeemed in the quarter. Furthermore, last week the company agreed with the State of Louisiana to accelerate the delivery of its Deepwater Horizon settlement commitments. The plan is now to prioritise the use of excess cashflow to address its remaining Deepwater Horizon liabilities in full. Overall, the combined sum of BP’s net debt, hybrids, lease liabilities and Gulf of America settlement liabilities fell by $9.3bn during the third quarter to $44.3bn. By the end of the year, this is expected to fall to $33bn-$35bn.
In a nod to these ‘other’ financial obligations, the company is currently not buying back its shares and is fully allocating excess cash to accelerate the strengthening of its balance sheet, a process that has accelerated with higher commodity prices. We believe this is the right decision – it saves $3bn a year and will create a strong platform to invest with discipline into the group’s ‘distinctive’ deep hopper of oil and gas opportunities.
We believe decarbonisation can’t happen at the flick of a switch – oil and gas will remain part of the global energy mix for decades, with demand driven by population growth and higher incomes, particularly in developing countries where the desire for energy intensive goods and services like cars, international travel, and air conditioning is rising. We also believe the production of the materials needed to transition to net zero can’t happen without hydrocarbons. At the same time, reduced investment in new production, partly because of environmental concerns, and natural decline rates, are increasingly leading to constrained supply.
Against this backdrop, investor disillusion with BP’s tilt towards low carbon energy, particularly in terms of capital discipline and returns (as evidenced by $18bn of impairments since 2023), and its poor recent governance track record, has had a negative impact on the share price over the medium term relative to the peer group. However, the recent arrival of a new CEO, combined with operational high-grading, reduced financial gearing, and ongoing M&A speculation suggests that the valuation gap between BP and its peers should narrow.
Source: Bloomberg
