
Morning Note: Market News and an Update from Halma.
Market News
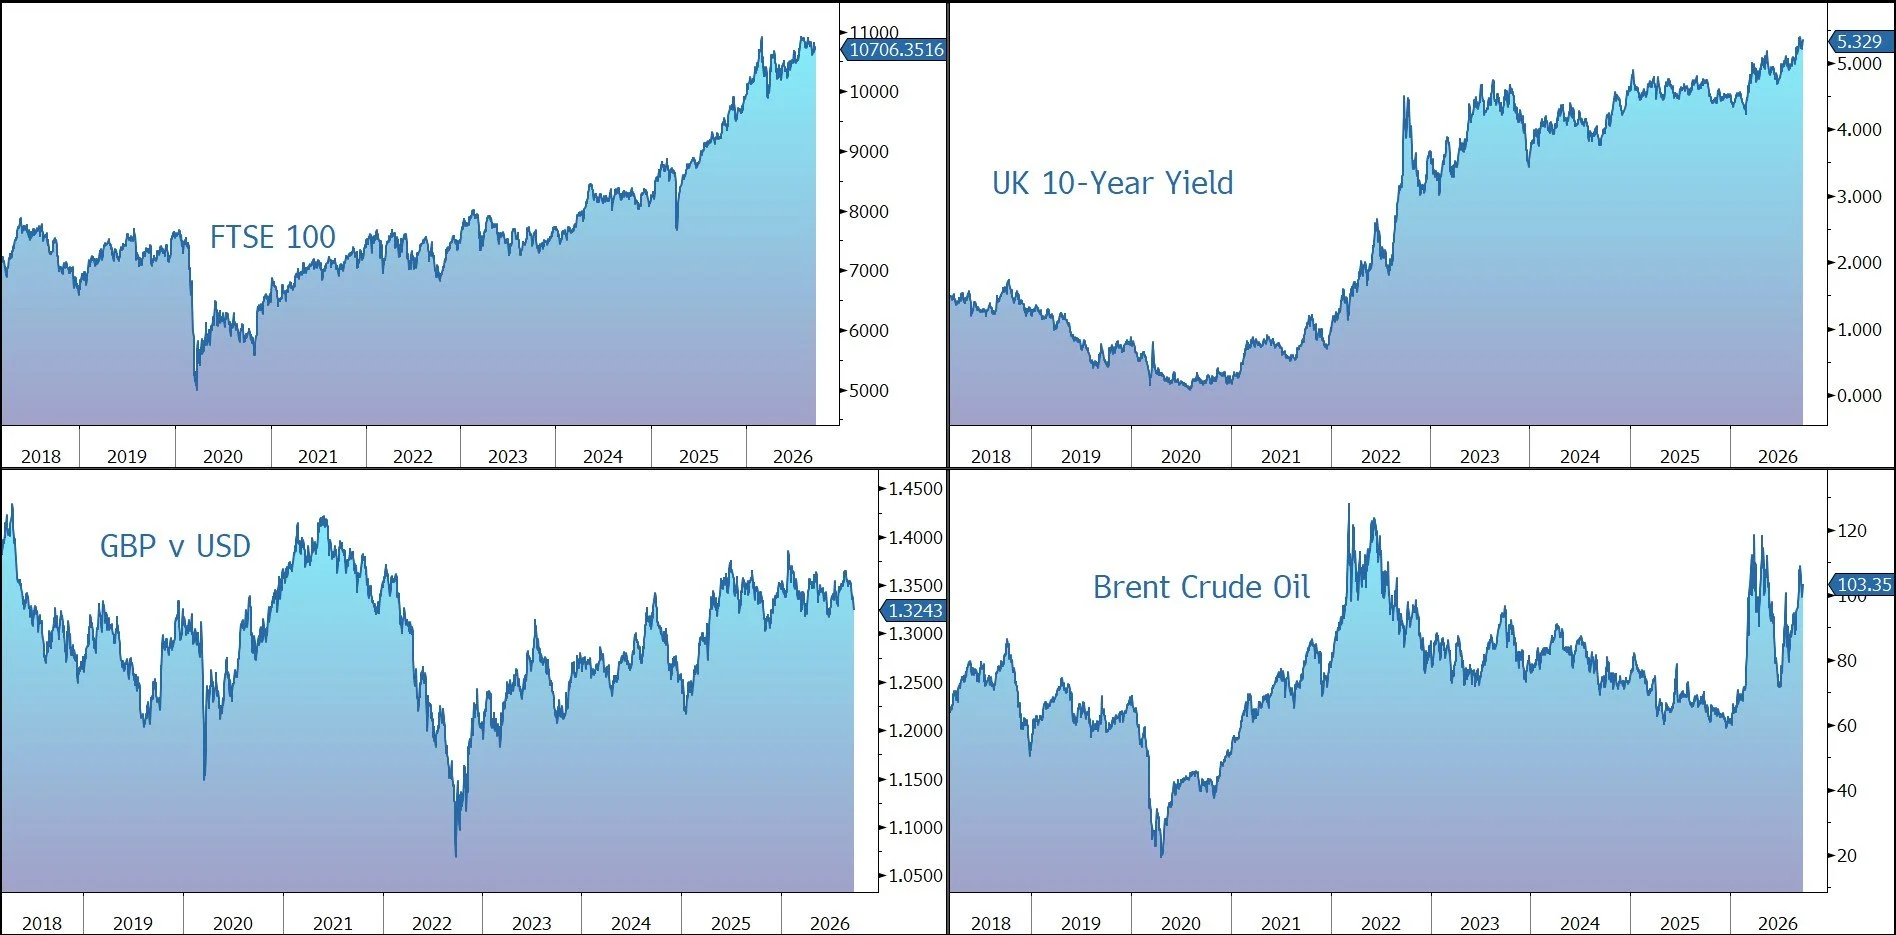
A global bond sell-off intensified, jolting investors as robust US economic data and weak demand at a debt auction drove Treasury yields across much of the curve to their highest levels in almost two decades. S&P Global data showed US private-sector activity expanded at its fastest pace in more than five years in September, with both the services and manufacturing sectors improving while facing stronger inflationary pressures. Markets are now pricing in around a 70% chance of a Fed rate hike in October, up from 55% a day earlier. The 10-year rose 16 basis points yesterday and currently yields 5.12%, while gold slumped below $4,300 an ounce.
Meanwhile, uncertainty surrounding US-Iran negotiations continues to keep oil prices elevated, adding further pressure to inflation expectations. President Masoud Pezeshkian maintained a firm stance, saying Tehran would not allow freedom of navigation through the Strait of Hormuz while sanctions and a US blockade remain in place. Brent crude is $103 a barrel, while the Trump administration is reportedly weighing a 90-day diesel export ban.
The US and China agreed to extend their trade truce by two months, according to Scott Bessent, as Xi Jinping arrived for his first state visit in 11 years. Personally greeted by Donald Trump, Xi said he expects the trip to produce fruitful results.
US equities dropped last night – S&P 500 (-0.8%); Nasdaq (-1.1%) – with Energy the only sector in positive territory. The sombre mood continued in Asia this morning: Hang Seng (-0.3%); Shanghai Composite (-1.0%). The Nikkei 225 (+1.0%) played catch-up after a long holiday, while the Korean market was closed.
The FTSE 100 is currently slightly higher at 10,716, while Sterling trades at $1.3250 and €1.1625. PM Andy Burnham hinted he doesn’t want his government to repeat the tax rises of recent Labour budgets, as John Healey prepares for a tricky financial statement on 28 October. 10-year Gilt yields are 5.25%.
Source: Bloomberg
Company News
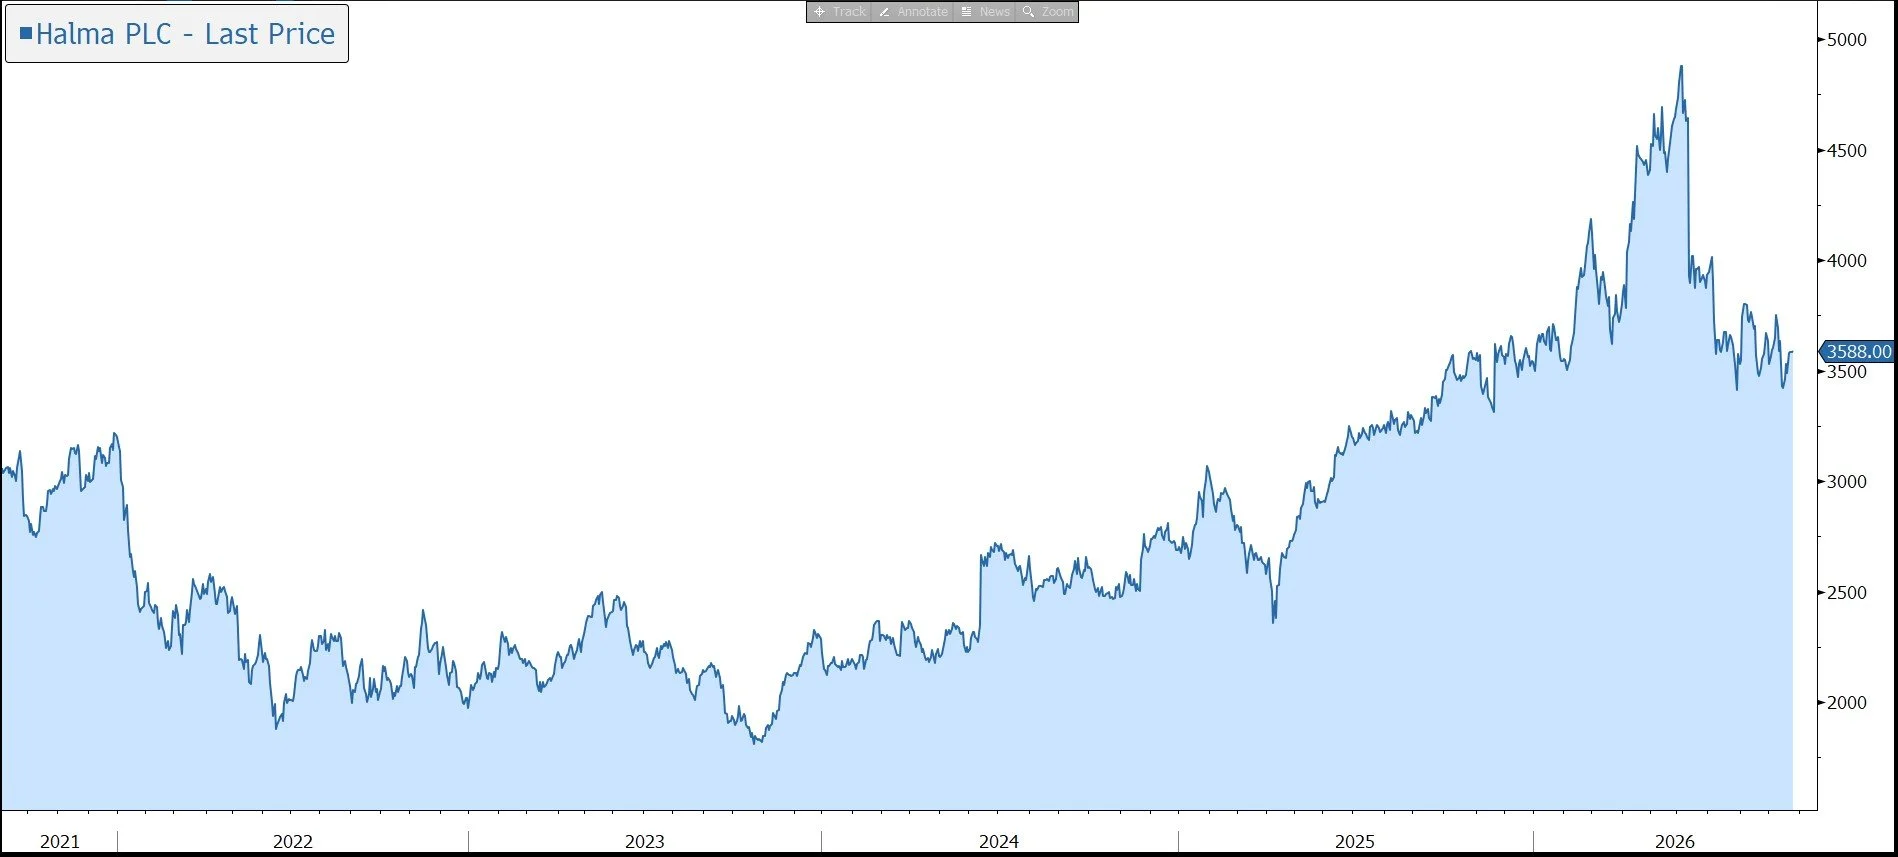
Halma has today released a positive trading update ahead of its half year-end on 30 September 2026 and increased its profit margin guidance for the full year. In response, the shares are unchanged in early trading.
Halma is a global group of 50 or so life-saving technology companies, with a focus on safety, healthcare, and the environment. The group’s technology is used to save lives, prevent injuries, and protect people and assets across a broad range of sectors including commercial and public buildings, utilities, healthcare/medical, science/environment, process industries, and energy/resources.
Products include control panels for fire safety systems, corrosion monitoring systems, gas detection systems, moisture control systems, and blood pressure monitoring systems. As a result, the company is highly diversified across different industrial cycles.
The main growth drivers include increasing health and safety regulation, demand for healthcare from an ageing population, and demand for life-critical resources. Strong market positions deliver upgrade and replacement sales opportunities as customers seek to maintain regulatory compliance and conform with best practice. As a result, customer spending is often non-discretionary and drives sustained demand throughout the economic cycle. Over time, this has driven consistent profit growth and shareholder returns.
Earlier in the year, the company revealed that one of the group’s companies, Avo Photonics, accounted for 20% of revenue in the last financial year. The company was acquired in 2011 and has benefitted from a close relationship with a large “hyperscaler” technology customer. The business has delivered premium growth amounting to a large proportion of the group’s organic revenue growth.
Halma has a fantastic dividend track record, having increased the payout by 5% or more every year for the last 47 years.
Today’s statement highlights the group has made strong progress in the first half of its financial year to 30 September, delivering broad-based growth against a backdrop of continued economic, geopolitical, and market uncertainty.
Based on progress so far and current expectations for the remainder of the year, the company continues to expect low double-digit percentage organic constant currency revenue growth for the year as a whole. This includes premium growth of approximately five percentage points from the photonics business, implying an organic constant currency photonics growth rate of approximately 30%, a slowdown compared to the previous financial year.
The adjusted EBIT margin for the full year is now expected to be in the range of 23.5% to 24.0%. This compares to previous guidance for margin to be in line with the 2026 financial year at around 22.7%, with the increase reflecting continued good operational delivery and favourable product and portfolio mix across all three sectors, including the positive impact of recent acquisitions and disposals.
The statement also highlights that order intake remains ahead of both revenue in the year to date and the comparable period last year.
The company has a strong balance sheet – at the end of the last financial year, gearing was only 1.16x net debt to EBITDA, well within the target of ‘up to 2x’. This enables continued investment, both organically and by acquisition, to support continued growth. The company has maintained strong M&A momentum, completing six acquisitions in the year to date, investing a record £515m. The healthy acquisition pipeline remains across all three sectors. To increase focus, the company has also completed three disposals in the period, realising approximately £83m, net of disposal costs.
Source: Bloomberg
