
Morning Note: A Round-up of Global Financial Market News.
Market News
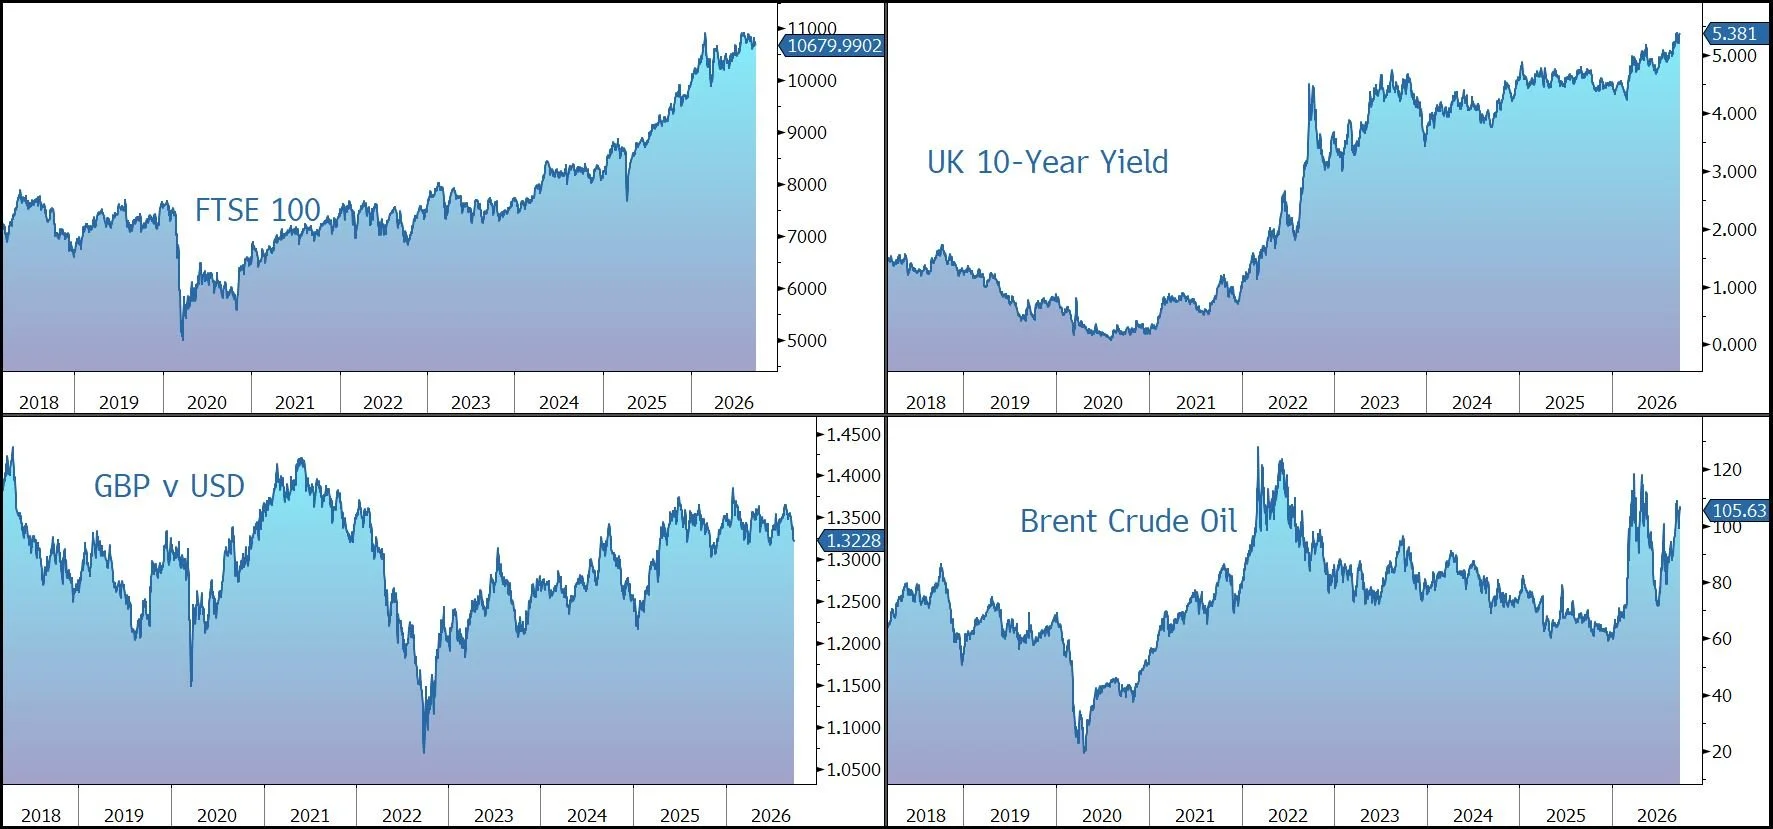
After a two-day surge, the oil price pulled back on hopes that negotiators at the UN General Assembly are reportedly pushing for a breakthrough on a phased Hormuz reopening deal. Brent crude currently trades at $105 a barrel.
As the inflation impulse eased, global bond markets stabilised providing investors with some respite after a bruising stretch. The 10-year Treasury yield has slipped back to 5.17%, following a jump of more than 20 basis points over the previous two sessions. Gold is holding at $4,270 an ounce, while the dollar has steadied after five straight gains. Today’s economic data - US Durable Goods Orders and the final University of Michigan Sentiment reading – will be closely watched, with any upside surprise in capex orders likely to reinforce the resilience narrative.
Prediction markets reportedly put the probability of the Democrats winning both chambers of Congress in the midterm elections at above 60%, up from the low 40s in July. Analysts note this would likely produce legislative gridlock but would not materially alter large fiscal deficits.
Donald Trump welcomed Xi Jinping to a state dinner attended by US tech leaders including Elon Musk, Jensen Huang, and Tim Cook. Trump said his meeting with Xi was “great,” while the Chinese leader urged the US president to formally “oppose” Taiwan independence.
US equities were pretty flat last night – S&P 500 (-0.02%); Nasdaq (+0.01%). Laggards included financials and consumer discretionary, while mega-cap tech and semis were relatively resilient. Costco was little changed after hours as earnings beat estimates but paid memberships rose less than expected. S&P futures are modestly higher this morning.
In Asia this morning, the Nikkei 225 (+1.3%) was firm as Japan’s Finance Minister Katayama confirmed President Trump expressed concern about yen weakness to PM Takaichi – it currently trades at Y158 to the dollar. Elsewhere, the Hang Seng (-1.4%) fell, while South Korea, Taiwan, and mainland China were closed for a holiday.
The FTSE 100 is currently 0.4% higher at 10,720, while Sterling trades at $1.3220 and €1.1615. UK consumer confidence came in at -13 in September, beating the survey of -16 and improving from -14 in August. This is the third consecutive monthly improvement, with four of five sub-measures rising.
The Times reports that the tax paid by banks in Britain has jumped as profits across the industry have risen, according to official figures that come amid mounting City speculation the government will target lenders with higher levies in the budget.
Source: Bloomberg
