
Morning Note: Market News and an Update from Bunzl.
Market News
Equity markets remain volatile as renewed AI sentiment jitters weigh on technology stocks ahead of a critical week of US mega-cap earnings. South Korea’s Kospi fell 3.7%, dragged down by SK Hynix after data centre firm Elice’s 32% debut collapse in Seoul — the worst-ever opening day for a sizable Korean IPO — underscored investor anxiety over AI valuations. Elsewhere in Asia, equities were weak – Nikkei 225 (-1.4%); Hang Seng (-1.0%) – while the Nasdaq futures are currently flat.
Brent crude climbed to $110 a barrel, the highest since May as escalating conflicts in the Middle East overshadowed signs of robust energy flows from the Persian Gulf. Iran continued to assert control over the Strait of Hormuz, with maritime authorities reporting multiple attacks on commercial ships. The European gas is €88/MWh, the highest since 2022.
The yield on the 10-year US Treasury held around 5.12% after climbing in the previous session, as investors assessed the Federal Reserve’s policy outlook ahead of its 27-28 October meeting. The dollar strengthened, while gold drifted down to $4,125 an ounce.
Japan enjoyed a record-demand 20-year JGB auction (bid-to-cover 5.84), which flattened the super-long curve. Bank of Japan Governor Kazuo Ueda also noted that underlying inflation was “quite close” to the central bank’s 2% target, signalling the possibility of further monetary tightening.
The FTSE 100 is currently 0.4% lower at 10,724, while Sterling trades at $1.3345 and €1.1885. UK gilts face a flattening bias after stronger-than-expected labour data – unemployment fell to 4.7% versus a 4.9% estimate – reinforcing interest rate expectations. Markets are now pricing 112 basis points of hikes by the end of 2026. The 10-year currently yields 5.42%.
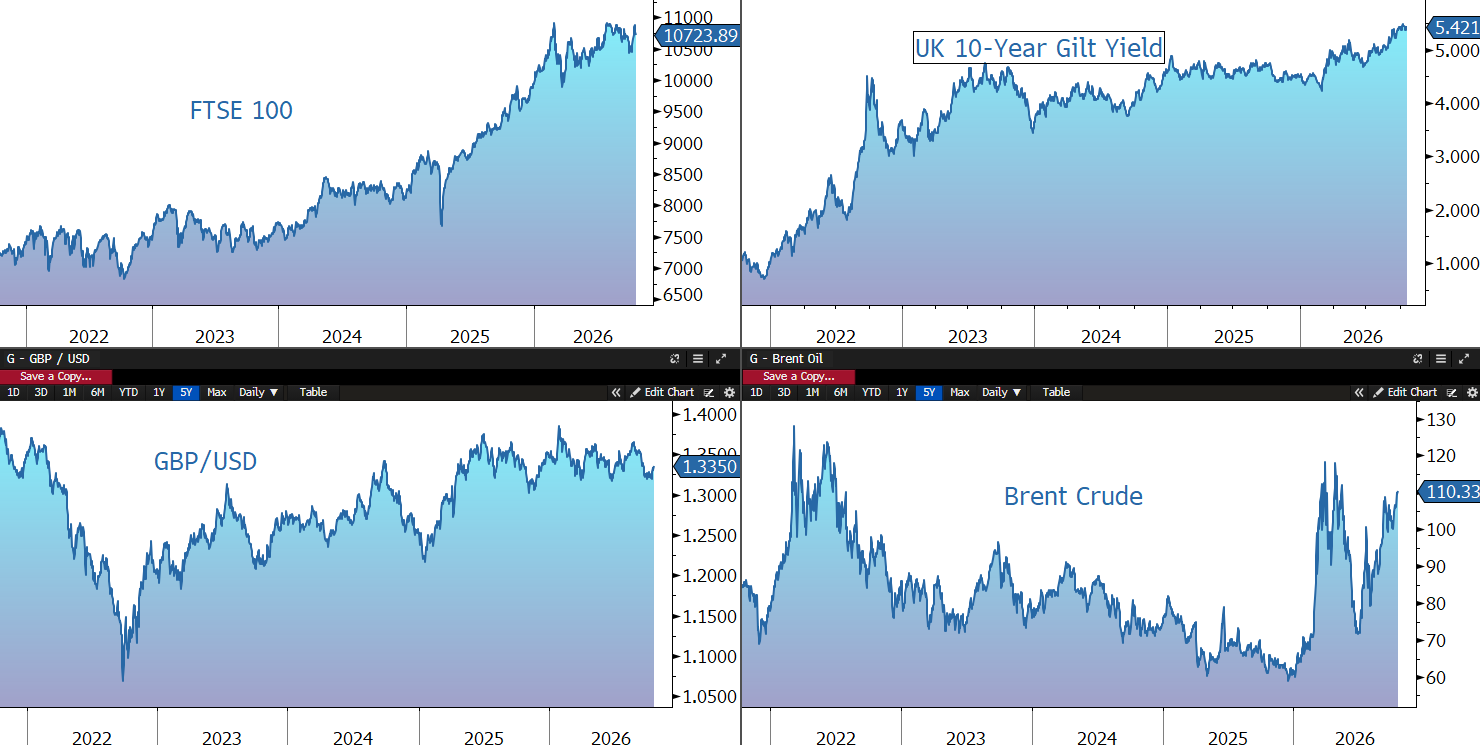
Source: Bloomberg
Company News
Bunzl has this morning released a trading statement for the three-month period to 30 September 2026 which highlights a resilient performance. The company has reiterated its guidance for the full year and is progressing with its £500m share repurchase programme. In response, the shares have been marked down by 2% in early trading.
Bunzl is a specialist international distribution and services group. The company provides an efficient and cost effective one-stop-shop solution to enable its customers to reduce or eliminate the ‘hidden’ costs of sourcing and distributing a broad range of goods that are essential to the successful operation of their businesses but which they do not themselves resell – think disposable tableware, rubber gloves, and plastic trays. The strategy is to expand the business through organic growth, consolidating markets through focused acquisitions, and continuously improving operating efficiency. The group is also supporting customers looking to transition towards packaging better suited to the circular economy, with around half of Bunzl’s packaging sales made from alternative materials.
Approximately 30% of revenue is delivered through the sale of own-brand products, while the company processes almost 80% of orders digitally, supporting customer stickiness and increasing low touch customer ordering.
The company is currently operating in an uncertain macroeconomic backdrop with challenging end markets and volatile input prices.
In the third quarter, group revenue grew 3.1% at constant exchange rates. Underlying revenue, which adjusts for the number of trading days, increased by 3.7%, supported by both inflation, reflective of year-on-year product cost increases, and volume growth, which continues to be driven by a strong performance in the North America Distribution business.
Acquisitions contributed 0.4% to revenue growth, while fewer trading days in the period impacted revenue by 1.1%.
The operating margin was in line with management expectations for the period.
Following the upgraded guidance provided at the half year, the group continues to perform in line with expectations and reiterates its full year outlook. Modest underlying revenue growth is expected, supported by some inflation, alongside a small benefit from acquisitions. Group operating margin for the year is expected to be broadly flat year-on-year compared to the 7.6% operating margin reported in 2025.
The company has a strong balance sheet – at the half-year stage, leverage was 1.8x adjusted net debt to EBITDA, below its target range of 2.0x to 2.5x. The group has a strong dividend paying track record, having grown its payout for 33 years in a row.
The company has a strategy to make value-accretive acquisitions to supplement growth. Earlier this month, the company completed the acquisition of Blueleaf Care, a leading distributor of care and nursing home products supplied primarily to care homes and the broader health and social care sector in the UK.
The company has completed £225m of its £500m share buyback programme, with the remainder expected to be completed by next July. The group continues to prioritise value-accretive bolt-on acquisitions and retains appropriate balance sheet headroom to fund acquisition opportunities.
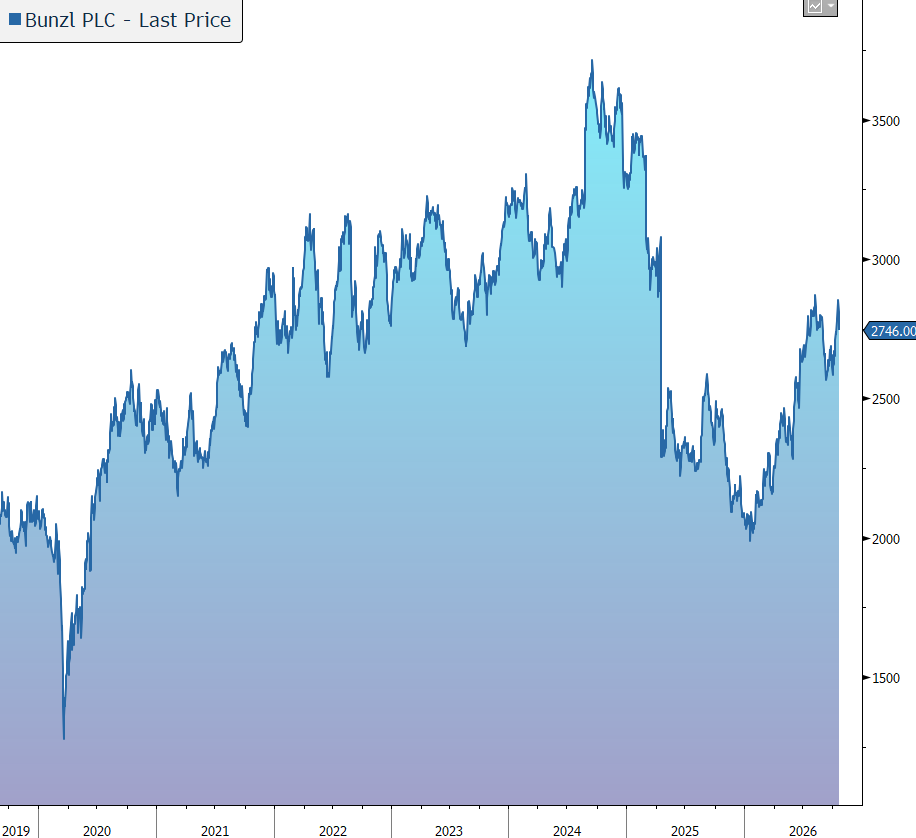
Source: Bloomberg
