
Market News
US equities were firm last night – S&P 500 (+1.3%); Nasdaq (+1.6%) – but rolled over after hours, with the Nasdaq futures currently down 1%. NVIDIA shares continued to tumble (-9% after-hours) on reports the company’s board may oust longtime CEO Jensen Huang amid an investigation into two extramarital affairs and potential national security and export-control exposure. The turmoil comes when financing, hyperscaler capex, valuations, and returns on AI investment were already under scrutiny. Potential beneficiaries, AMD, Broadcom, and Alphabet were all firm. The Anthropic IPO, described by some on the Street as the ‘Jenga block’ holding up the AI trade, becomes even more pivotal in this context.
In Asia this morning, Taiwan’s tech-heavy benchmark slumped 2.6% while other regional indices were also weak: Nikkei 225 (-0.7%); Hang Seng (-1.2%); Shanghai Composite (-0.7%); Kospi (-0.6%).
The dollar extended gains – the DXY index moved above 103 for the first time since April 2025 – as hotter-than-expected US CPI fuelled bets on a Fed rate hike in December. Gold fell for a third day, dropping below $4,000 an ounce, while the yield on the 10-year US Treasury is 5%.
Brent crude eased to $93 a barrel as Saudi Arabia reported a 26% surge in October production and US-Iran diplomacy showed tentative signs of progress.
The FTSE 100 is currently 0.7% higher at 10,872. This is despite a meaningful drag from companies trading ex-dividend this morning, including BP (1.18% price impact), Bunzl (0.73%), GSK (0.89%), Sainsbury (1.17%), Shell (0.81%), and Unilever (0.79%).
Rolls-Royce is trading 3% higher as the company reaffirmed its profit guidance and launched a £1.5bn share buyback. The company said it will revisit mid-term targets at its forthcoming Capital Markets Day.
UK Q3 GDP came in at +0.7% quarter on quarter, in line with estimates, with September monthly GDP beating at +0.2%. AI-driven business spending and resilient consumer demand were cited as contributors. Sterling trades at $1.3265 and €1.1970, while the 10-year Gilt yields 5.21%.
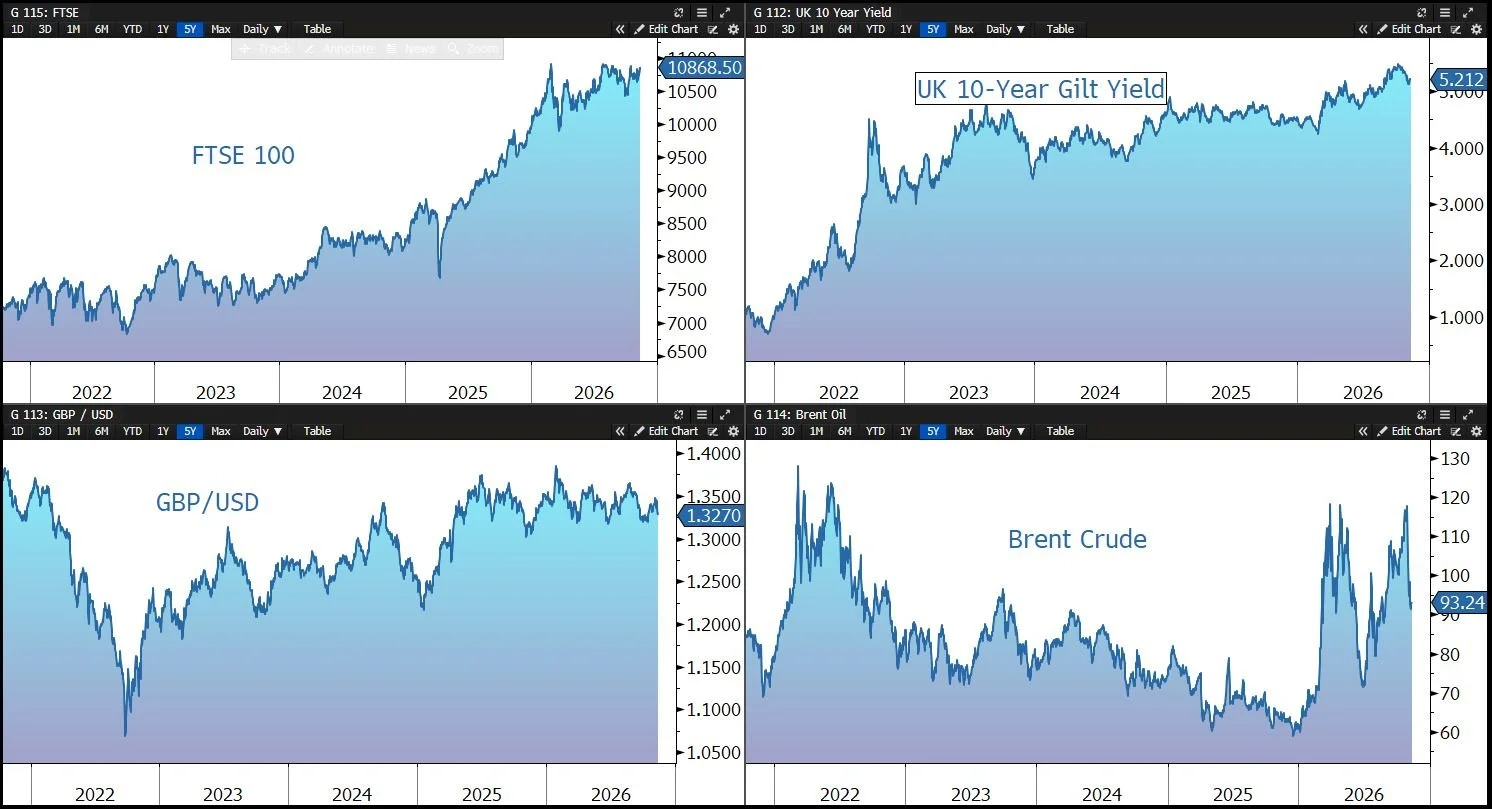
Source: Bloomberg
