
Market News
The yield on the 10-year US Treasury note rose back up to 5%, after hot inflation data consolidated bets that the Federal Reserve will deliver multiple additional rate hikes in the current cycle. Both headline and core consumer prices rose more than expected in October, adding to evidence that soaring energy prices are being transmitted into core sectors of a resilient economy. The data followed hawkish comments from Fed Governor Waller, who advocated for a 25 bps rate hike in December with the possibility of a larger 50 bps move should prices rise more than the central bank expects. Gold is trading at $4,060 an ounce, partially recovering yesterday’s 2.6% drop.
Global equities also sold off in response to the inflation print – S&P 500 (-0.4%); Nasdaq (-0.7%) – but have rebounded this morning, with the Nasdaq futures currently trading 1.5% higher. The bounce was driven by AI optimism, anchored by CoreWeave’s upbeat revenue guidance and TSMC’s $1bn investment commitment in Anthropic and OpenAI. Asian equities extended gains for a third session: Nikkei 225 (+1.3%); Shanghai Composite (+0.5%); Kospi (+2.6%).
Anthropic is seeking to raise up to $100bn through a combination of IPO, private placement, and overallotment. One venture investor has warned the IPO could mark a peak for the AI trade, with lockup expiries posing a potential correction risk.
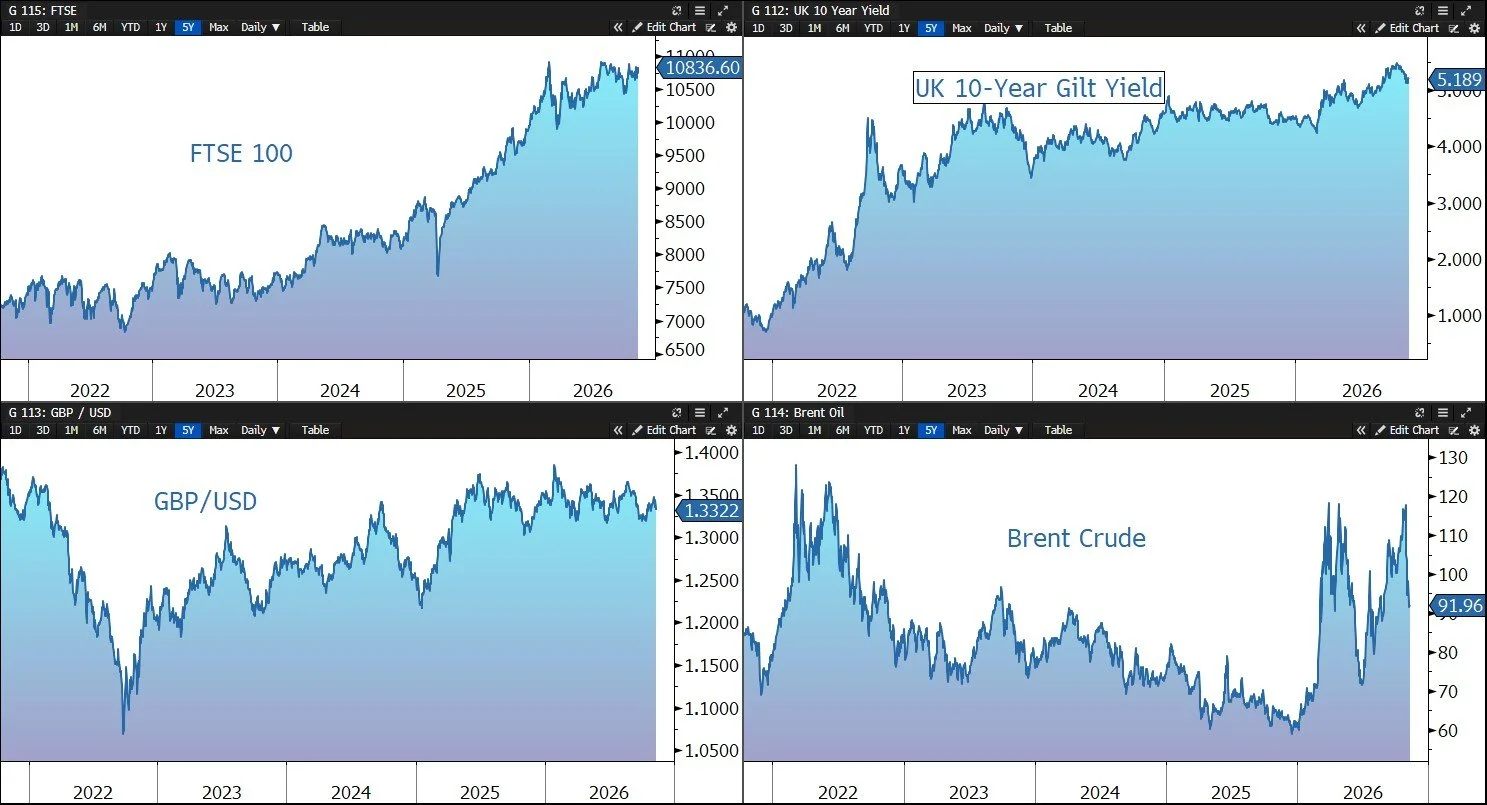
US-Iran tensions remain elevated following limited US strikes on a Strait of Hormuz island, keeping Brent Crude around $92 a barrel.
The FTSE 100 is currently 0.8% higher at 10,837. Taylor Wimpey (-2%) expects full-year operating profit at the lower end of its guidance range, while ITV (-4%) warned advertising revenue will be down 5%-10% in the final quarter. Sterling trades at $1.3325 and €1.1950, while the 10-year Gilt yield moved up to 5.2%.
Source: Bloomberg
Company News
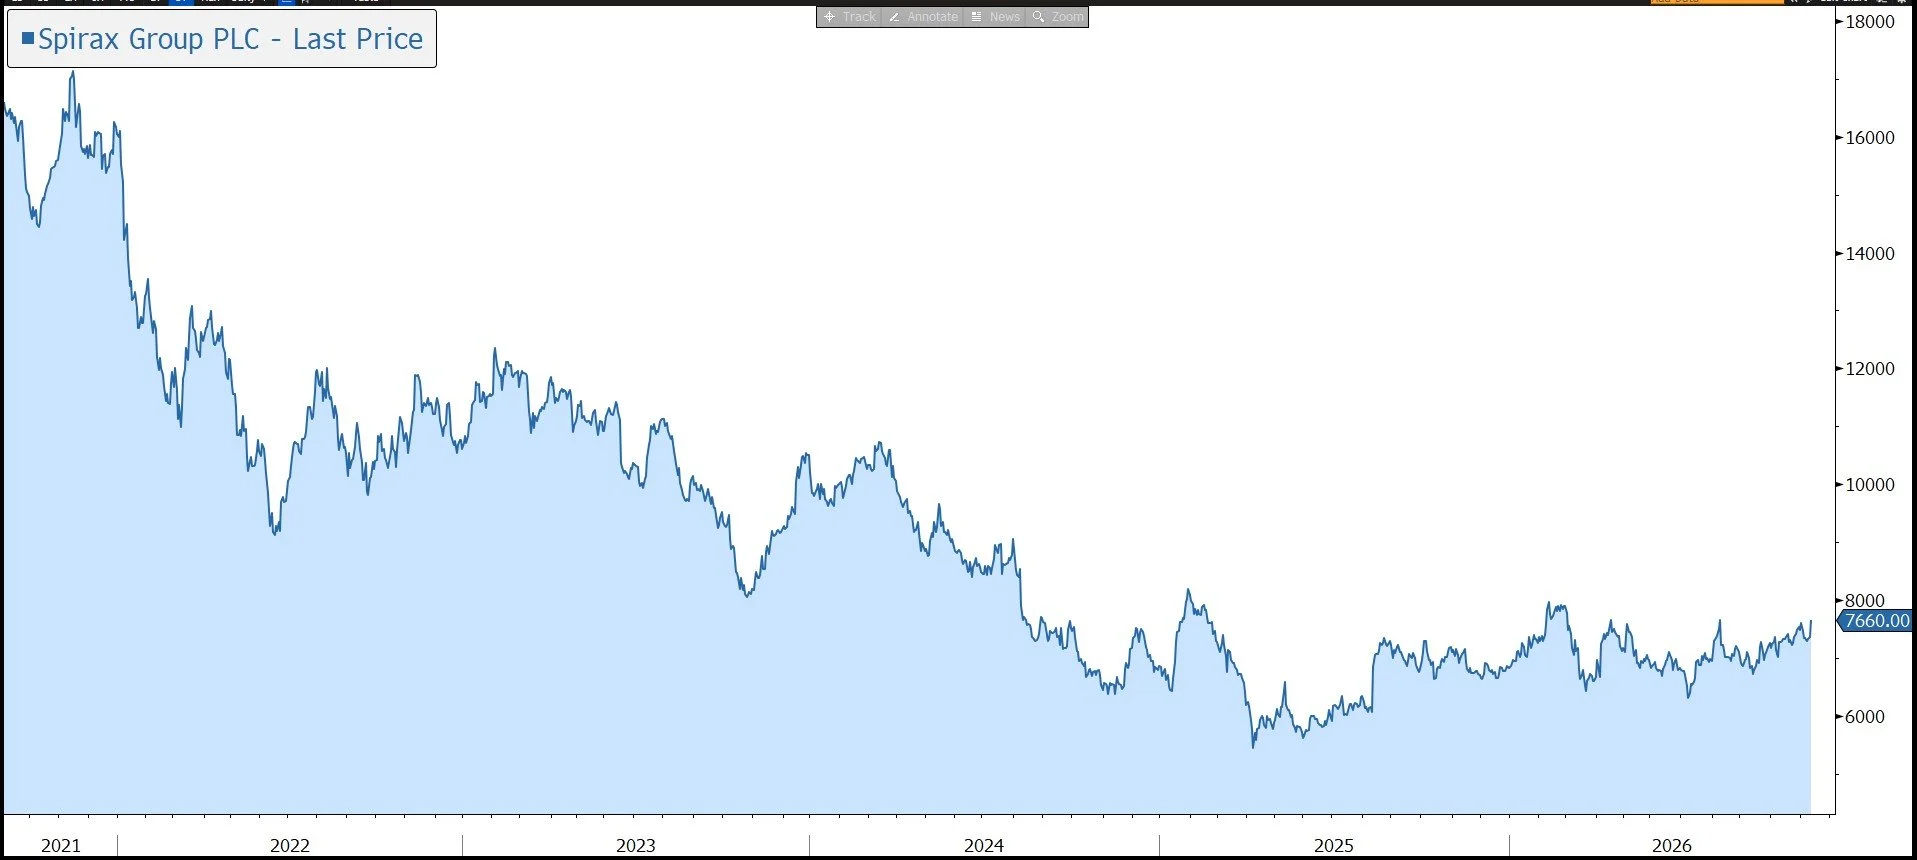
Spirax Group has released a trading update in respect of the four months ended 31 October 2026. Despite the challenging macroeconomic environment, organic growth is running in line with expectations across all businesses and the group is confident in the delivery of its full-year guidance. In response, the shares are up 4% in early trading.
Spirax (formerly Spirax-Sarco Engineering) is a UK-listed industrial company, with annual sales of £1.7bn. The group is a world leader in each of its three businesses which it believes have a total addressable market of £18bn. In Steam Thermal Solutions (50% of revenue), Spirax Sarco and Gestra are leaders in the control and management of steam. In Electric Thermal Solutions (26%), Chromalox and Thermocoax provide electrical process heating and temperature management solutions. Finally, Watson-Marlow Fluid Technology Solutions (24%) provides niche peristaltic pumps and associated fluid path technologies.
The group’s products are used in almost every industry worldwide: from the food sector where steam products are used in blanching, baking, packaging, and cleaning; to the pharmaceutical industry where pumps and associated fluid path equipment are critical to the production of life-saving medicines; through to the aviation industry where electrical heating elements are used in the de-icing of aeroplanes. Sales to defensive sectors account for 60% of revenue.
85% of revenue is generated from maintenance and operational (opex) budgets rather than capital (capex) budgets. Of that 85%, 50% comes from essential repair and maintenance activities, while 35% comes from small projects that improve existing systems. As a result, the group has a long history of stable, sustainable growth and strong profitability.
However, in response to a weaker macroeconomic environment, the group took early action across all three businesses to appropriately right-size capacity and overhead support costs, as well as implementing temporary cost containment actions and reducing variable compensation.
So far this year, macroeconomic uncertainty has remained elevated, with conflict in the Middle East and higher energy costs weighing on industrial production growth.
In the ten months ended 31 October, the company continued to execute against its strategic priorities and generated organic sales growth and adjusted operating profit margin in line with expectations and ahead of the first half.
Within the Steam Thermal Solutions business, organic sales growth in the four months to October was higher than the first half, as expected. Growth was supported by shipments from the larger order book at the end of June and continuing order momentum. China sales (approximately 15% of STS sales in 2025) are on track to be in line with 2025 for the full year, with continuing growth in MRO (Maintenance, Repair, and Overhaul) and stabilising large project sales. Consistent with the group’s guidance, the second-half margin will be ahead of the first half, underpinning a full-year margin broadly in line with 2025.
In Electric Thermal Solutions, the strong organic sales growth of the first half continued in the four months to October. The business is continuing to drive strong order intake in Process Heating and Heat Trace across all sectors. Growth in Equipment Heating is benefitting from higher Wafer Fabrication Equipment manufacturers (Semicon) demand. Excluding sales to Semicon customers (approximately 13% of ETS sales in 2025), ETS organic sales growth remains above the group’s mid-single-digit medium-term target. Operational gearing and the ongoing delivery of manufacturing efficiencies will support a higher second half margin for ETS, compared to the first half.
Demand remained robust in both Process Industries and Pharmaceutical & Biotechnology (Biopharm).
In Watson-Marlow, organic sales growth in Biopharm was higher in the four months to October, compared to the first half, with orders remaining ahead of sales. The business continues to see strong growth in end-user and consumables sales, while expansion-related sales are improving as expected. Process Industries also saw continuing strong organic sales growth, supported by market share gains. Higher second-half organic sales growth in the division will drive a second-half margin slightly ahead of the first half.
The group is financially robust, with net debt at the end of October of £541.6m, slightly lower than at the half-year stage, with gearing of 1.3x net debt to EBITDA, in the middle of its 1.0x-1.5x target range. The group has a strong track record of dividend growth, with 58 years of progress.
Looking ahead, despite the weak IP environment, the company is confident it will achieve its guidance for 2026. The target is mid-single-digit organic revenue growth, well ahead of IP, and an adjusted operating profit margin higher than the 2025 margin of 20.0%. Cash conversion is expected to be around 90% for the full year.
Over the medium term, the aim is to grow ahead of underlying markets, with high-single digit profit growth delivered through mid-single digit organic sales growth (close to 2x IP) and an improving margin of 22%-23%. This will drive cash conversion of over 80% and an improving return on capital.
Source: Bloomberg
