
Morning Note: Market News and an Update on Financial Markets.
Market News
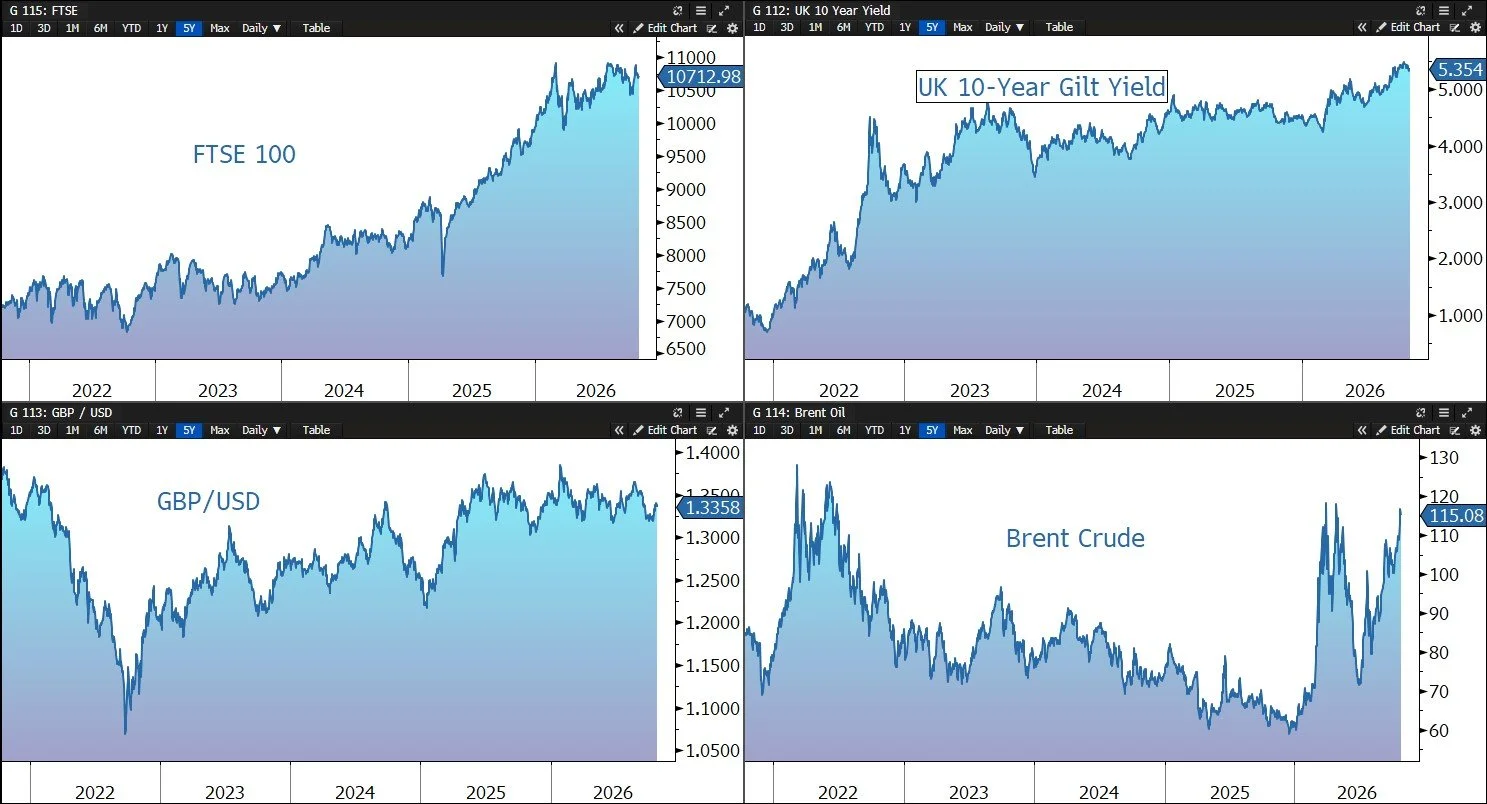
Oil remains one of the key macro catalysts across markets. Brent crude currently trades at $115 a barrel, drifting back slightly this morning from Iran war highs. Over the weekend, President Trump said he would soon decide whether to pursue a deal with Tehran or restart military operations, as threats from Iran and the Houthis against Americans in the Middle East continue to escalate.
We note markets are increasingly expecting elevated hydrocarbon prices through next year – summer 2027 crude is now priced in the mid-90s, and the traded gasoline curve is now flat at elevated levels through to next summer. Although output from the Gulf has increased, prices have not normalised, in part, due to extremely elevated shipping costs related to the risk of physically getting the oil out of the region. The concern is that inflationary pressures prove to be more than transitory, placing pressure on central banks to further tighten monetary policy.
With that in mind, markets will this week focus on the Federal Reserve’s upcoming policy decision, with the central bank widely expected to keep interest rates unchanged before potentially raising them in December. Elsewhere, central banks in the Eurozone and Japan are also expected to maintain current rates.
The yield on the 10-year US Treasury remains just below 5%, after sliding for three straight weeks, as mounting concerns about AI spending continued to drive safe-haven demand for bonds. Gold is trading around $4,000 an ounce, hovering near its lowest level in more than three months. The metal faces headwinds from ETF outflows; worldwide holdings fell more than 10 tonnes on Friday alone, the largest single-day draw since 4 March, reducing GLD assets to $136.1bn.
In the equity market, Nasdaq 100 Index futures slipped 0.2% after the underlying gauge posted a second consecutive weekly loss, while a US chip index notched its longest losing streak since last November. In Asia this morning, markets were mixed: Nikkei 225 (-0.8%); Hang Seng (+0.6%); Shanghai Composite (+0.2%); Kospi (-1.5%). The FTSE 100 is currently 0.4% higher at 10,739.
This week is another busy one for corporate earnings, with releases from Google owner Alphabet, Microsoft, and Amazon. The market’s focus is on AI capex disclosures and the timeline for returns. Fears that spending will swamp strong revenue growth have weighed on sentiment. Reports are also due from Apple, Visa, Mastercard, BP, Shell, Heineken, Assa Abloy, Reckitt Benckiser, Unilever, AstraZeneca, and Cameco.
The UK budget on Wednesday adds a further layer of event risk for gilts (10-year yield is 5.35%) and sterling (currently $1.3355 and €1.1915). UK gilt dealers expect an expansion of the Treasury bill market to be announced, potentially reducing gilt yields and easing pressure on public finances.
Moody’s affirmed France’s sovereign rating at Aa3 over the weekend, averting a feared downgrade. Weekend protests remained largely peaceful — approximately 110,000 in Paris and 300,000 nationally per the Interior Ministry — but President Macron faces unresolved fiscal and social pressures
Source: Bloomberg
