
Market News
Donald Trump and Vladimir Putin discussed Ukraine during their first in-person meeting in 15 months. Trump said he’s looking to both Putin and Xi Jinping for help ending the war ahead of today’s trilateral meeting. The US president also hailed his “great” relationship with Xi and downplayed the Nvidia spying controversy in a Fox News interview.
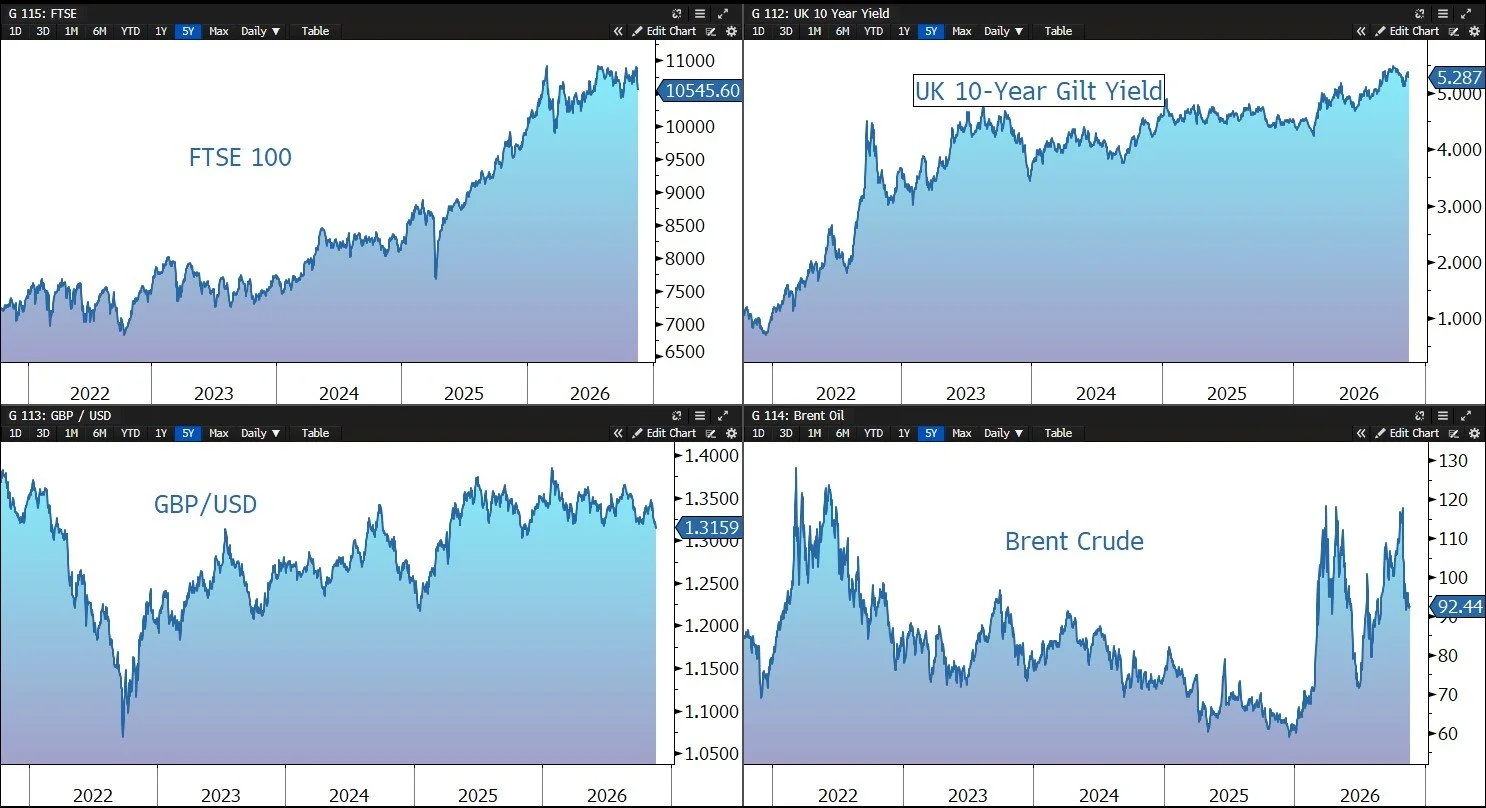
Brent crude steadied around $92 a barrel as investors assessed reports that President Trump was considering additional military strikes against Iran, with Israeli PM Benjamin Netanyahu reportedly urging him to participate in a four- to seven-day military campaign. Despite these geopolitical concerns, the international oil benchmark remained close to its lowest levels since late August.
France’s political and fiscal turmoil may push the euro further down, with Morgan Stanley and Commerzbank seeing $1.08 next year, versus $1.10 currently. Investors are demanding a much bigger premium to hold French debt as election and budget risks mount. The yield spread between the 10-year German bund (3.37%) and the French OAT (4.87%) is currently 150bps.
Gold is trading at $3,735 an ounce, close to its lowest level since September 2025, as the US dollar continued to strengthen on expectations of further Federal Reserve rate hikes. Minutes from the FOMC’s October meeting showed that nearly all policymakers supported additional rate increases in the coming months to bring inflation back toward the 2% target. The yield on the 10-year US Treasury is 5.08%.
US equities were mixed last night – S&P 500 (-0.2%); Nasdaq (+0.4%). Anthropic raised a record $107.3bn in its IPO and private placement, topping SpaceX’s debut and valuing the Claude maker at about $1.5 trillion. The stock starts trading today and is expected to soon join the Nasdaq 100. The shares are indicated to open between 20%-26% higher in grey market trading. Nasdaq 100 futures jumped 2% ahead of Anthropic’s debut. In Asia this morning, markets were mixed: Nikkei 225 (+0.7%); Hang Seng (-2.0%); Shanghai Composite (-0.3%); Kospi (+1.4%).
The FTSE 100 is currently little changed at 10,546. Companies trading ex-dividend this morning include National Grid (1.36% price impact), RS Group (1.13%), Scottish Mortgage IT (0.12%), Tate & Lyle (1.21%), and Vodafone (1.69%). Sterling trades at $1.3150 and €1.1970.
Source: Bloomberg
Company News
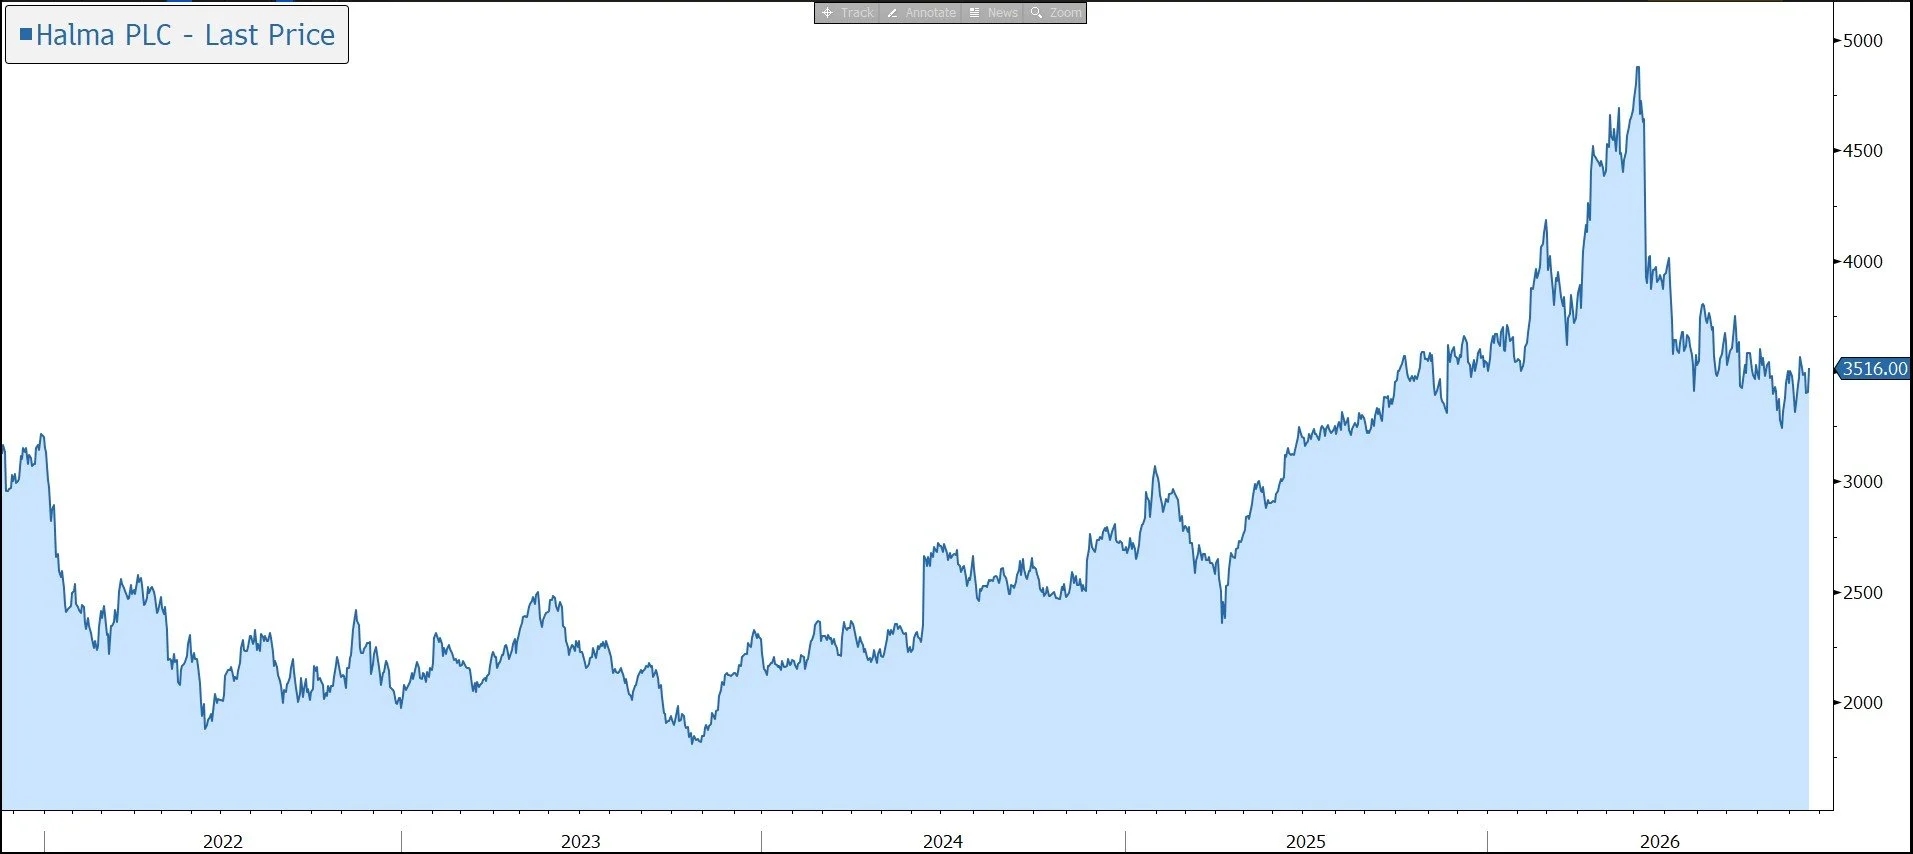
Halma has today released results for the financial half-year to 30 September 2026. The figures came in above market expectations as the company delivered record revenue and profit. The balance sheet remains strong and the half-year dividend was raised by 7%. Looking ahead, the company remains well placed to deliver its existing guidance. In response, the shares have been marked up by 1% in early trading.
Halma is a global group of 50 or so life-saving technology companies, with a focus on safety, healthcare, and the environment. The group’s technology is used to save lives, prevent injuries, and protect people and assets across a broad range of sectors including commercial and public buildings, utilities, healthcare/medical, science/environment, process industries, and energy/resources.
Products include control panels for fire safety systems, corrosion monitoring systems, gas detection systems, moisture control systems, and blood pressure monitoring systems. As a result, the company is highly diversified across different industrial cycles.
The main growth drivers include increasing health and safety regulation, demand for healthcare from an ageing population, and demand for life-critical resources. Strong market positions deliver upgrade and replacement sales opportunities as customers seek to maintain regulatory compliance and conform with best practice. As a result, customer spending is often non-discretionary and drives sustained demand throughout the economic cycle. Over time, this has driven consistent profit growth and shareholder returns.
Earlier in the year, the company revealed that one of the group’s companies, Avo Photonics, accounted for 20% of revenue in the last financial year. The company was acquired in 2011 and has benefitted from a close relationship with a large “hyperscaler” technology customer. The business has delivered premium growth amounting to a large proportion of the group’s organic revenue growth. Halma is using this period of premium growth to further invest in other growth opportunities.
Today’s statement highlights the group has made strong progress in the first half of its financial year to 30 September, delivering broad-based growth against a backdrop of continued economic, geopolitical, and market uncertainty.
Revenue grew by 15.8% to £1,433m, with organic growth of 12.3%. This included price increases averaging between 1% and 2%. Excluding one-off revenue realised from a transaction in the Environmental & Analysis Sector in 2025/26, revenue increased by 13.1% on an organic basis. Avo Photonics (+30%) amounted to five percentage points of this growth.
Growth was broad-based across all three sectors. The Environmental & Analysis Sector delivered a particularly strong result (+18.0%), which was well spread across the portfolio including premium growth in photonics. Revenue growth in the Safety Sector was 10.1%, with good performance across all its subsectors, including fire safety and worker safety. Healthcare delivered a good performance (+5.8%), supported by a continued and steady recovery in healthcare markets.
The adjusted operating margin rose by 180 basis points to 24.1%. This excludes the one-off profit from the Nuvonic transaction (UV disinfectant systems). Adjusted profit before tax grew by 21% to £327.7m, above the market forecast of £316m.
The group’s return on total invested capital rose from 16.2% to 17.3%, above the 12%-17% target range and well above its estimated weighted average cost of capital of 10.2%.
Halma has a fantastic dividend track record, having increased the payout by 5% or more every year for the last 47 years. Today, the group has declared a half-year payout of 10.3p, 7% higher than last year.
Cash conversion was strong at 85% and is expected to exceed the group’s target of 90% for the full year. Net debt rose from £769m to £966m, with financial gearing of only 1.26x net debt to EBITDA, well within the target of ‘up to 2x’.
This enables continued investment, both organically and by acquisition, to support continued growth. R&D investment rose by 8% to £63.9m. The group made six acquisitions in the half-year for a maximum total consideration of £516m. Since the period-end, two further deals have been made for £55m and the pipeline remains ‘healthy’.
Based on progress so far and current expectations for the remainder of the year, the company continues to expect low double-digit percentage organic constant currency revenue growth for the year as a whole. This includes premium growth of approximately five percentage points from the photonics business, implying an organic constant currency photonics growth rate of approximately 30%, a slowdown compared to the previous financial year. The adjusted operating margin for the full year is still expected to be in the range of 23.5% to 24.0%.
Source: Bloomberg
