
Morning Note: Market News and an Update from Currys.
Market News
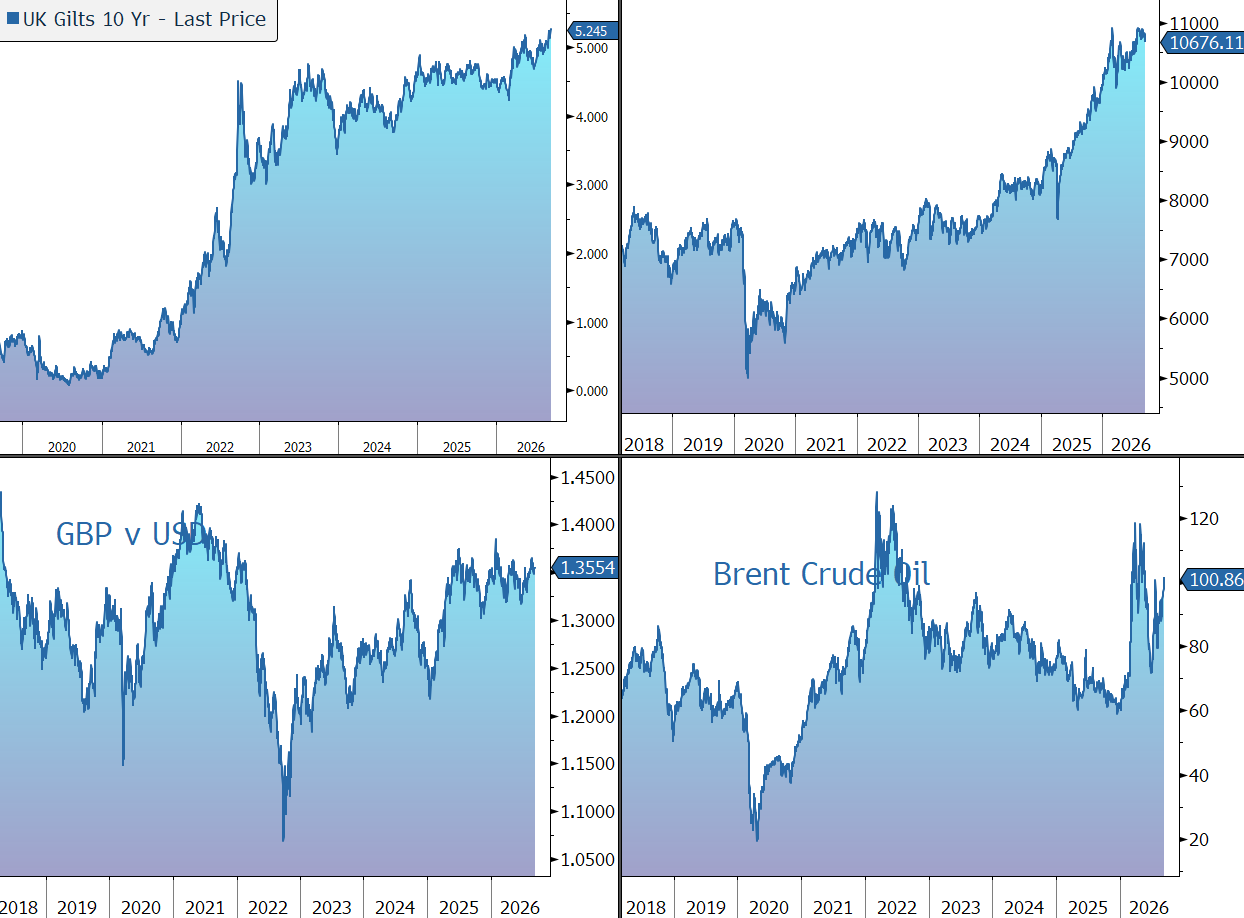
Brent crude remains above $100 a barrel, hovering at its highest level since May as the intensifying conflict between the US and Iran raised concerns over further disruptions to energy supplies. President Trump predicted the conflict would not end until after the November midterm elections and said significant relief in gasoline prices was unlikely before then, signalling limited prospects for near-term de-escalation.
The surging oil price added to concern that inflation will accelerate and lead to higher global interest rates. The yield on the 10-year US Treasury moved up to 4.84%, with the US Treasury’s announcement of plans to triple government debt buybacks to as much as $6bn adding to yield pressure. The dollar index is close to a four-month low, while gold trades above $4,400 an ounce. Key US inflation readings could provide further insight into the Federal Reserve’s next policy move, with the US producer price index report for August due later today, followed by the consumer inflation report tomorrow. The ECB rate decision is also due at lunchtime today. With a 25 basis points hike to a deposit rate of 2.5% pretty much priced in, the focus will be on the post-decision press conference and updated quarterly projections.
Donald Trump promised a $5,000 dividend for every US adult citizen if Republicans retain control of Congress. The move could cost $1.3 trillion and add another layer of risk as today’s 30-year Treasury auction was already shaping up as a difficult sale.
US equities drifted lower last night – S&P 500 (-0.5%); Nasdaq (-0.6%) – with the Energy sector the sole riser. In Asia this morning, stocks were also weak: Hang Seng (-1.2%); Shanghai Composite (-0.5%); Kospi (-0.3%). The outlier was Japan (Nikkei 225, +0.2%). The FTSE 100 is currently little changed at 10,683, while Sterling trades at $1.3550 and €1.1645. Companies trading ex-dividend this morning include Prudential (0.65%), M&G (1.91%), and Greggs (1.07%).
Governor Andrew Bailey, in testimony to the Treasury Committee, highlighted the impact of the Iran war on crack spreads and refined product prices, underscoring the Bank of England’s inflation vigilance. The 10-year Gilt yield stands at 5.24%. UK house prices remain under pressure, with the RICS gauge at -28 in August and further declines expected over the next three months. This comes as Britain is heading into winter with soaring gas prices, high household bills, and thin fuel reserves — UK gas prices have more than doubled since the start of the year.
Source: Bloomberg
Company News
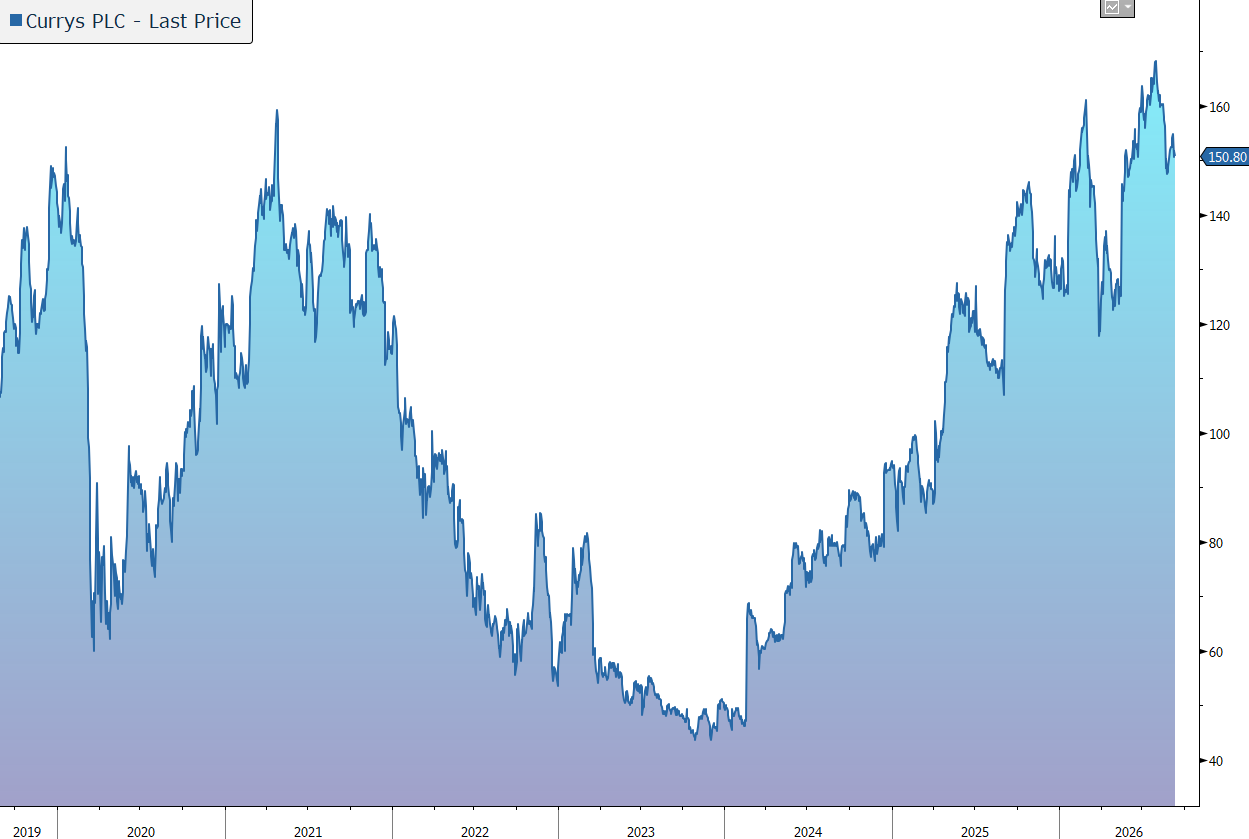
Currys has released a trading update which highlights a strong start to its financial year to end-April 2027. The company is part-way through its share buyback programme and is happy with the current market consensus for the full year. In response, the shares are little changed in early trading.
Currys is a leading multichannel retailer of technology products and services, operating online and through around 700 stores in six countries. As a result, the group is well placed to supply the technology that has become ever more central to people’s lives. In the UK & Ireland, the group trades as Currys, with a 17.5% market share, and operates its own mobile virtual network, iD Mobile. In the Nordics, the Elkjøp brand has a 28.0% share of the market. In the most recent financial year, the company generated revenue of £9.3bn.
Over the longer term, the company is targetting at least a 3% adjusted EBIT margin in both the UK & Ireland and the Nordics. The focus will be on free cash flow generation, with annual capital expenditure expected to remain below £100m and net cash above £100m.
From the beginning of August, Fredrik Tønnesen, Nordics CEO, was appointed Group Chief Executive Officer.
Today’s statement highlights that in the 17 weeks to 29 August 2026, like-for-like (LFL) sales rose by 7%.
In UK & Ireland, the company generated LFL sales growth of 6% over the last 17 weeks, driven by growth in both stores and online, with double-digit growth in new categories and B2B. The group enjoyed market share gains in all major categories, in a flat market that benefitted by c.2%pts from the World Cup and Summer heatwaves. Recurring Services revenue grew strongly with flexpay credit adoption up 30 basis points to 23.6% and iD Mobile reaching over 2.7m subscribers, a 16% year-over-year increase. The gross margin was stable as a result of tight cost control.
In the Nordics, LFL revenue growth was 9%, driven by white goods and mobile, with continued success in new categories, B2B and Services. Market share gains were generated in most countries and categories, in a market that saw strong growth against soft comparatives. Again, tight cost control helped to keep the gross margin stable.
Over time, the company has steadily reduced its financial leverage and now has a net cash balance sheet – £176m on 2 May 2026. The group’s pension liability is now very small, with contributions of only £13m p.a. required over the five years to March 2031. The company is aiming to maintain a year-end net cash balance of at least £100m for the foreseeable future and expects to be well above this level at the end of this financial year.
This level of cash allows the company to efficiently manage the working capital cycle of the business and protect the balance sheet in the event of unexpected market downturns. The company is currently undertaking a £50m share buyback programme, with £23m completed to date.
For the full year to end-April 2027, the company is comfortable with market consensus of adjusted PBT of £199m. The group is targeting continued growth in higher margin, recurring Services revenue, including reaching at least 2.8m iD Mobile subscribers before the year-end.
Source: Bloomberg
