
Morning Note: A Round-up of Global Financial Market News.
Market News
Scott Bessent said talks with Chinese counterparts on AI, trade and investment were “very successful” ahead of this week’s summit between Donald Trump and Xi Jinping. China’s state media described the discussions as candid and constructive.
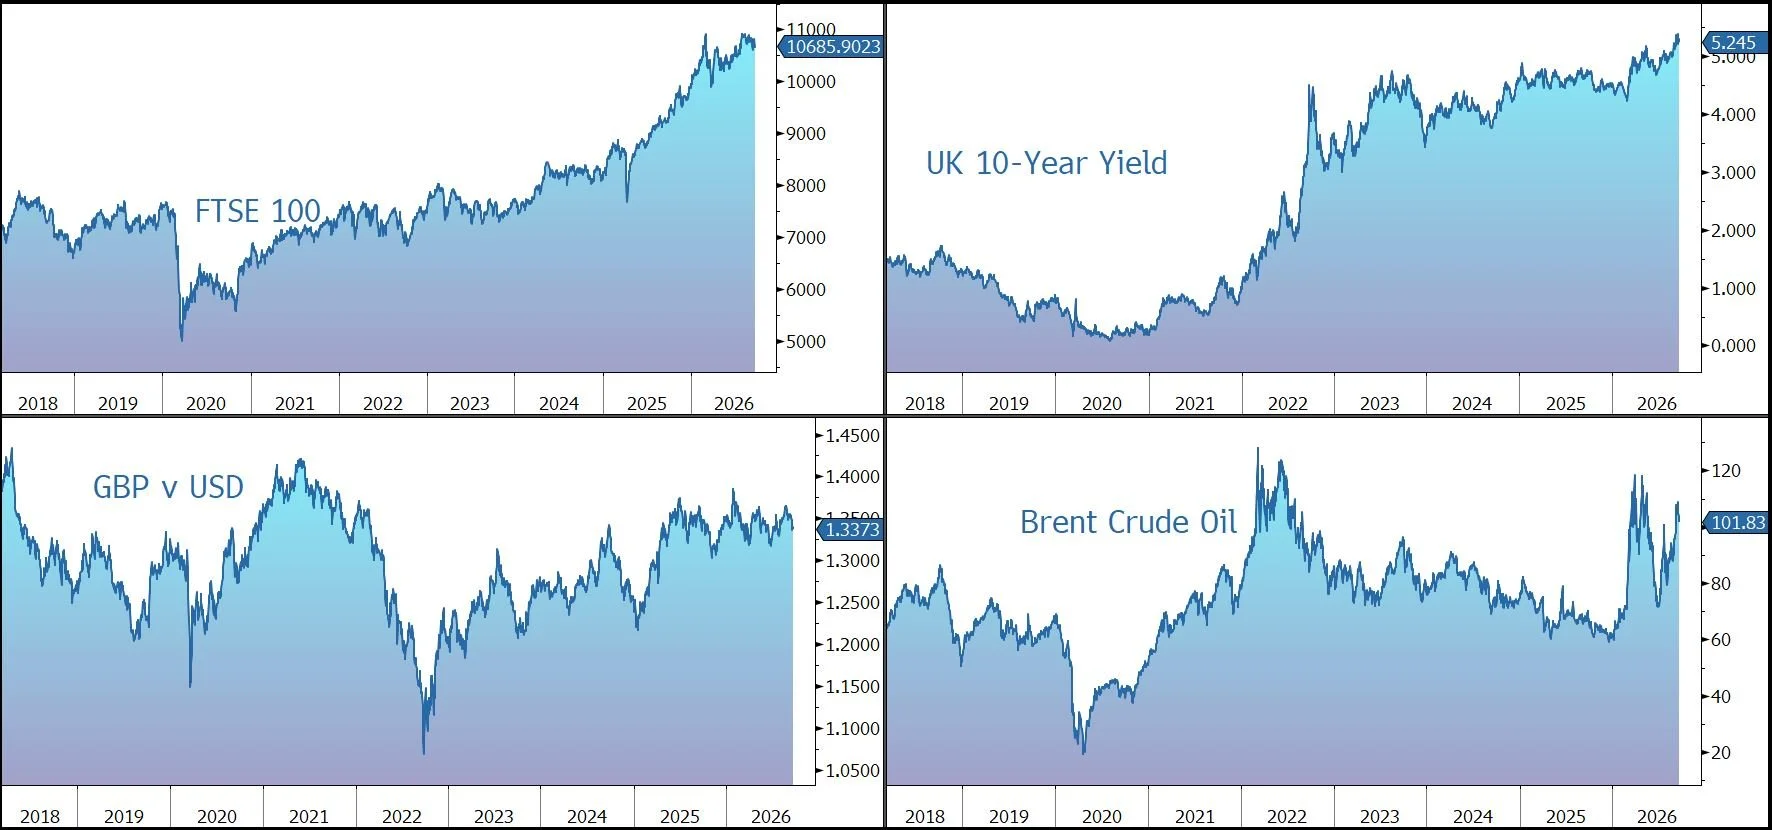
Brent crude dropped to $102 a barrel, declining for the fourth straight session, pressured by hopes that increased diplomatic efforts could help end the Middle East conflict and restore energy flows from the region. President Trump said he would “probably” be open to meeting Iranian President Masoud Pezeshkian on the sidelines of the UN General Assembly in New York this week. Meanwhile, Qatar’s energy minister said Bessent was “wrong” to predict the Strait of Hormuz would be worthless in two years.
Over the weekend, Minneapolis Fed President Kashkari said inflation has “broadened beyond oil prices into all aspects of the economy,” reinforcing the hawkish bias. We note disruptions to Black Sea grains exports are creating a second global supply shock alongside the Hormuz oil crisis, threatening higher food prices and shortages in import-dependent countries. Other Fed speakers this week will be scrutinised for endorsement or pushback on the market’s increasingly hawkish pricing of a further hike. The yield on the 10-year US Treasury is 4.97%, while gold has slipped to $4,350 an ounce.
In Germany, Friedrich Merz vowed to stay on as chancellor after his CDU won just 4.9% in Mecklenburg-Western Pomerania, leaving it out of a regional assembly for the first time in the country’s postwar history. 10-year Bund yields remain elevated at 3.47%.
45 US data center projects worth $68bn were blocked or delayed by local opposition between April and June 2026, according to Data Center Watch, creating a material bottleneck for AI infrastructure buildout.
In Asia this morning, equity markets were lifted by gains in technology shares: Nikkei 225 (+1.4%); Hang Seng (+0.7%); Shanghai Composite (+0.7%); Kospi (+1.4%). The futures market is currently pointing to a 0.6% gain in the S&P 500 at the open this afternoon. The FTSE 100 is trading 0.5% higher 10,700, with BP and Shell notable decliners of the back of the lower oil price.
UK housing asking prices rose 0.7% month-on-month in September, reversing August’s -2.0% decline. The Times reported that the UK is considering expanding its new ‘mansion tax’ to homes worth more than £1.5m from the £2.0m threshold it already announced. Sterling trades at $1.3370 and €1.1655, while the 10-year Gilt yields 5.25%. Markets are now pricing in five 25bp Bank of England interest rate hikes over the next 12 months.
Source: Bloomberg
