
Market News
Risk sentiment deteriorated overnight as a deepening sell-off in US chipmakers — down 12% over three days — pushed the Nasdaq 100 more than 10% below its recent peak. In Asia this morning, the drawdown continued: Nikkei 225 (-0.3%); Shanghai Composite (-0.8%); Kospi (-3.6%). The AI capex debate appears to be reaching an inflection point: Marvell’s reportedly $80bn all-stock acquisition of Lumentum, Oracle’s $20bn debt-and-equity raise, and Meta’s potential $20bn bond deal signal that Big Tech is doubling down on AI infrastructure even as the Nasdaq 100 enters correction and investors grow more selective about financing terms.
After the US close, Apple reported new sales records in China in the September quarter, with greater China revenue up 21% to a new high. The Mac division delivered double-digit growth. However, the stock fell 3% after hours as the company warned that ‘unprecedented’ memory chip costs will hit margins.
The yield on the 10-year US Treasury is currently 4.91%. Investors are now bracing for the US midterm elections today. Polls suggest Republicans face headwinds, with Trump’s tariffs and high oil prices linked to voter anxiety over prices and affordability. A Democratic sweep could bring greater scrutiny of AI spending and data-centre build-out, while a Republican hold would offer policy continuity more supportive of tech and chipmakers. Either outcome will reshape positioning in a market already in correction.
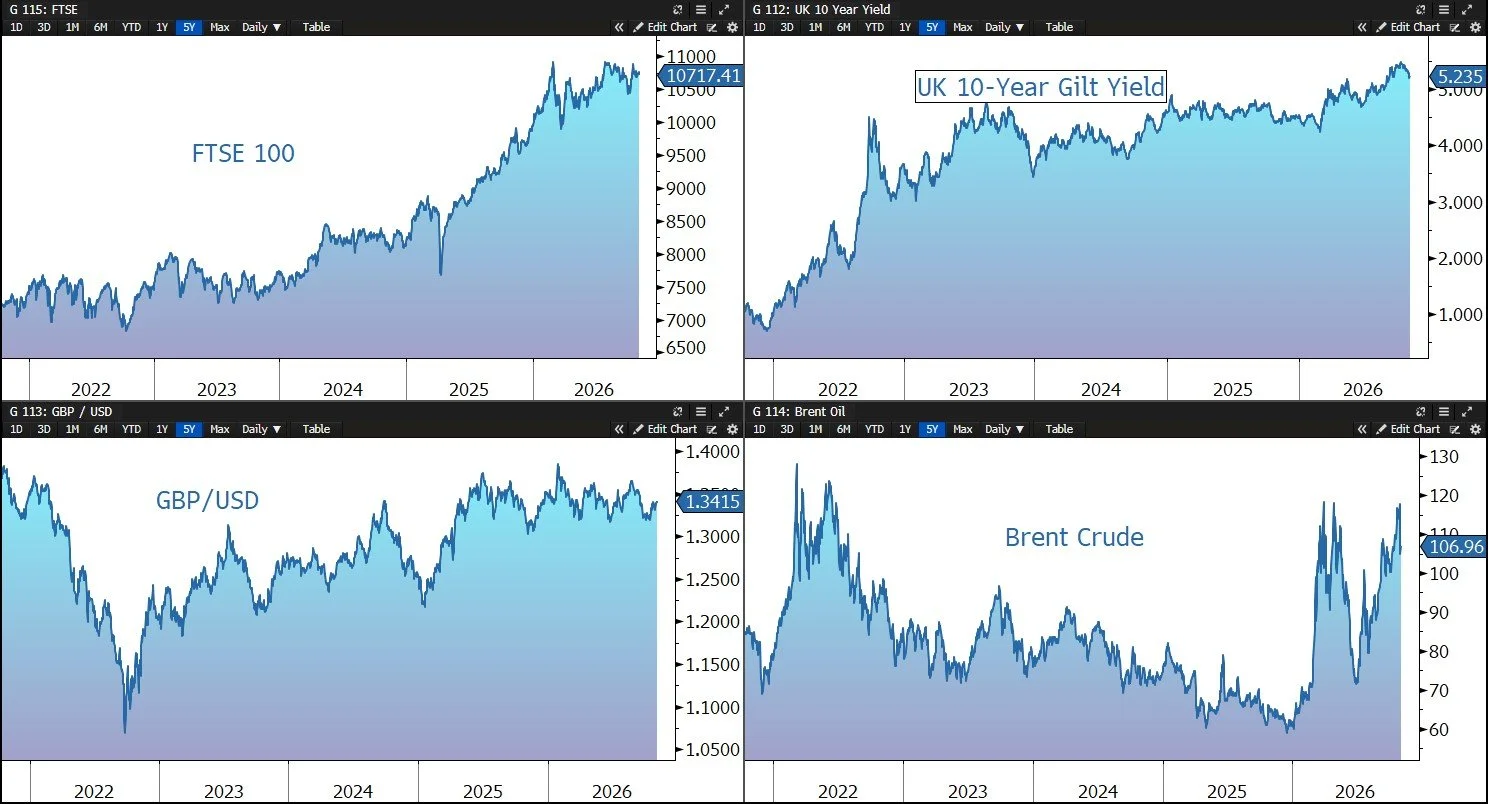
Brent crude regained some of yesterday’s heavy losses and currently trades at $107 a barrel, following reports of a US attack on Iran’s Qeshm Island. The reported strike appears to mark the latest in a series of limited military operations allegedly carried out by Washington while diplomatic negotiations remain ongoing. The 7% decline in the previous session came after signs of progress in US-Iran talks eased concerns over further supply disruptions.
In the US refining sector, CVR Energy, controlled by Carl Icahn, is reportedly near a deal to acquire Marathon Petroleum refineries for more than $4bn, according to the Wall Street Journal.
Gold has fallen back toward $3,900 an ounce, surrendering gains from the previous session. The World Gold Council reports that central banks bought gold at the fastest pace since late 2024 in Q3, accumulating a net 321 tons,
The FTSE 100 is currently 0.4% lower at 10,726. Associated British Foods reported full-year revenue of £19.6bn, in line with estimates, but warned that FY2027 adjusted operating profit is likely to be lower than 2026, mainly due to its sugar segment. The shares are trading 3% lower.
Ahead of Thursday’s interest rate decision, Sterling trades at $1.3420 and €1.1980, while the 10-year Gilt yields 5.24%. All 35 economists in a Bloomberg survey predict the first hike in over three years.
Source: Bloomberg
