
Morning Note: Market News and an Update from Lululemon.
Market News
Expectations for a Fed rate hike in September eased following Fed Governor Christopher Waller’s comments that he would support keeping rates steady if price pressures continued to ease. Swaps priced roughly even odds of a quarter-point hike in September, down from about 70% earlier this week. The US jobs report today is the critical test. US payrolls are expected to add 12,000 in August, compared with a 23,000 decline in July, according to Bloomberg Economics. Unemployment is estimated to rise to 4.2%.
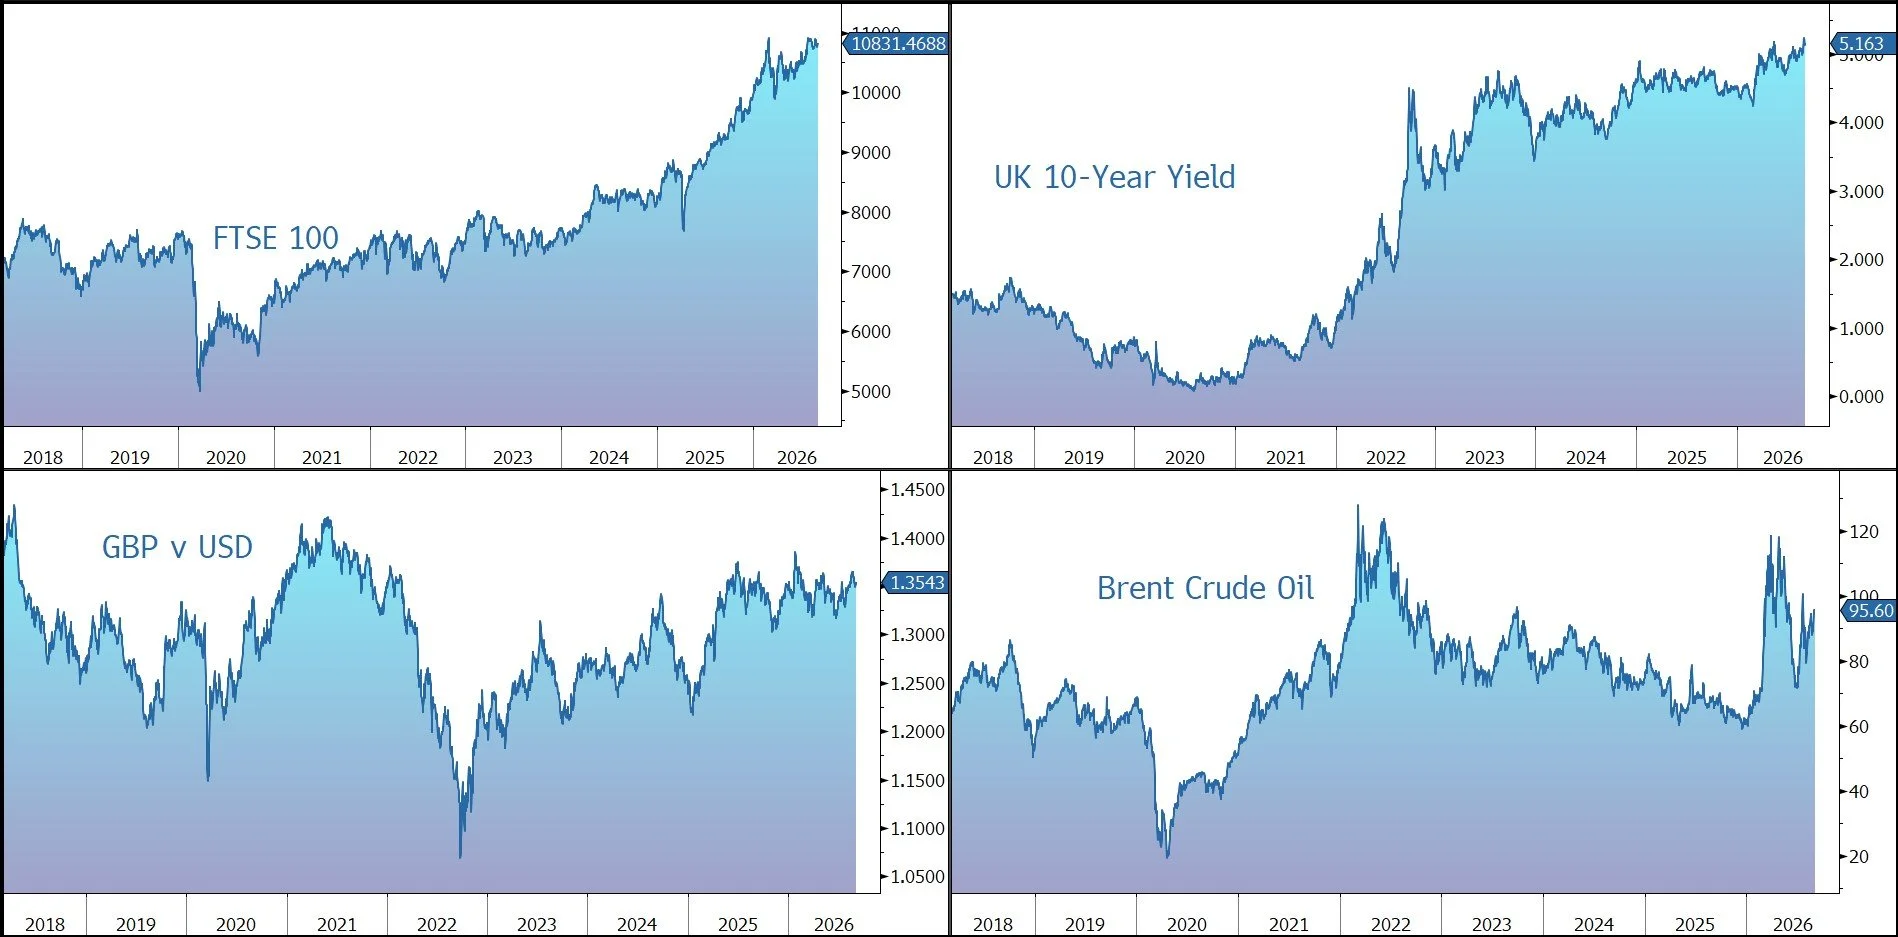
The yield on the 10-year US Treasury is currently 4.76%, while gold is trading at $4,470 an ounce. Norway’s sovereign wealth fund is considering an overhaul of its global bond portfolio, the FT reported. The newspaper estimated the cuts could reduce Norges Bank’s holdings of US Treasuries by about $80bn.
Brent crude held above $95 a barrel and was on track for a gain of more than 8% this week, underpinned by renewed hostilities in the Middle East and growing uncertainty surrounding shipping through the Strait of Hormuz. JD Vance downplayed the scope of the conflict in Iran, telling reporters, “I wouldn’t call it a war.”
The Japanese yen is trading at around 156 per dollar after surging for two consecutive sessions, putting it on track to gain about 2.5% for its strongest weekly performance since Tokyo and Washington carried out a joint yen-buying operation in late July. There is no confirmation that this week’s rally was driven by official intervention, although traders have speculated that authorities conducted a rate check, which typically precedes intervention.
US equities closed higher last night – S&P 500 (+1.1%); Nasdaq (+1.4%) – with all the Mag 7 names notching up gains. Anthropic is set to finalise an expansion of its revolving credit facility to $15bn before its IPO, people familiar said. Morgan Stanley is leading the process. In Asia this morning, stocks were also firm: Nikkei 225 (+1.3%); Hang Seng (+1.7%); Kospi (+1.6%). The FTSE 100 is currently little changed at 10,820.
Source: Bloomberg
Company News
Last night, Lululemon Athletica released results for the second quarter of its financial year to January 2027. Performance was below market expectations, albeit boosted by tariff refunds. Given the ongoing challenging environment, the company has once again revised down its full-year guidance. The shares slumped by 18% in after-hours trading.
Lululemon is principally a designer, distributor, and retailer of healthy lifestyle inspired athletic apparel and accessories. Apparel items include pants, shorts, tops, and jackets designed for a healthy lifestyle including athletic activities such as yoga, running, and training. The company also offers a range of products designed for being on the move, fitness-related accessories, and footwear.
The group operates 825 stores across 18 countries. In FY2025, revenue was $11.1bn, split between stores, online, and other revenue, which includes net revenue from outlets, temporary locations, sales to wholesale accounts, and license and supply arrangements.
The company’s new CEO, Heidi O'Neill, takes the reins next week.
During the three months to 2 August 2026, revenue slipped by 5% on a constant dollar basis to $2.42bn, versus the market forecast of $2.46bn. Comparable sales fell by 10% on a constant dollar basis. Store revenue and digital revenue were both down by 6%.
By category, Women’s Apparel fell by 4%, Men’s Apparel was down 1%, while Accessories slumped 13%. By region, sales declined by 8% in the Americas and by 2% in Greater China. Some relief was provided by a 6% increase in the Rest of the World.
The gross margin rose by 200 basis points to 60.5%, although this includes tariff refunds of $134.5m, which amounted to 560 basis points of gross margin tailwind. The operating margin fell by 190 basis points to 18.8%, with the tariff refund also having a 560 basis points positive impact. EPS declined by 6% to $2.92, with the result including an 86c related to tariff refunds and associated interest, net of tax.
The company added nine net new company-operated stores during the quarter. Inventories fell by 1% to $1.7bn and were down 7% on a unit basis. The group ended the quarter with $1.4bn in cash and cash equivalents, having repurchased $330m of its shares.
Looking forward, given the ongoing challenging environment, the company has revised down its guidance for the financial year to January 2027. Net revenue is now expected to be $10.35bn to $10.50bn, (versus $11.0bn-$11.15bn previously). Adjusted EPS is now expected to be between $9.48 and $9.73, versus the previous guidance of $10.95-$11.15. The guidance includes $0.86 per share from tariff refunds and associated interest, net of tax recognised in the last quarter, but does not reflect any further potential tariff refunds.
Source: Bloomberg
