
Morning Note: A Round-up of Global Financial Market News.
Market News
The Federal Reserve delivered its first rate hike since 2023, raising the federal funds rate by 25bp to a target range of 3.75%-4.00%. Following a unanimous vote, Chair Kevin Warsh signalled at least one additional increase this year and said that “inflation is too high” with too many categories showing annualised gains above 3%. Warsh stated the Fed “removed a dose of accommodation” to bring financial conditions in line with its objectives. President Trump publicly demanded rates of “1% or less” in response. Bond markets are now pricing in three additional hikes. Overall, Warsh’s resolve to tackle inflation reassured markets. Equities bounced, the yield on the 10-year US Treasury fell back below 5%, while gold has moved up to $4,330 an ounce.
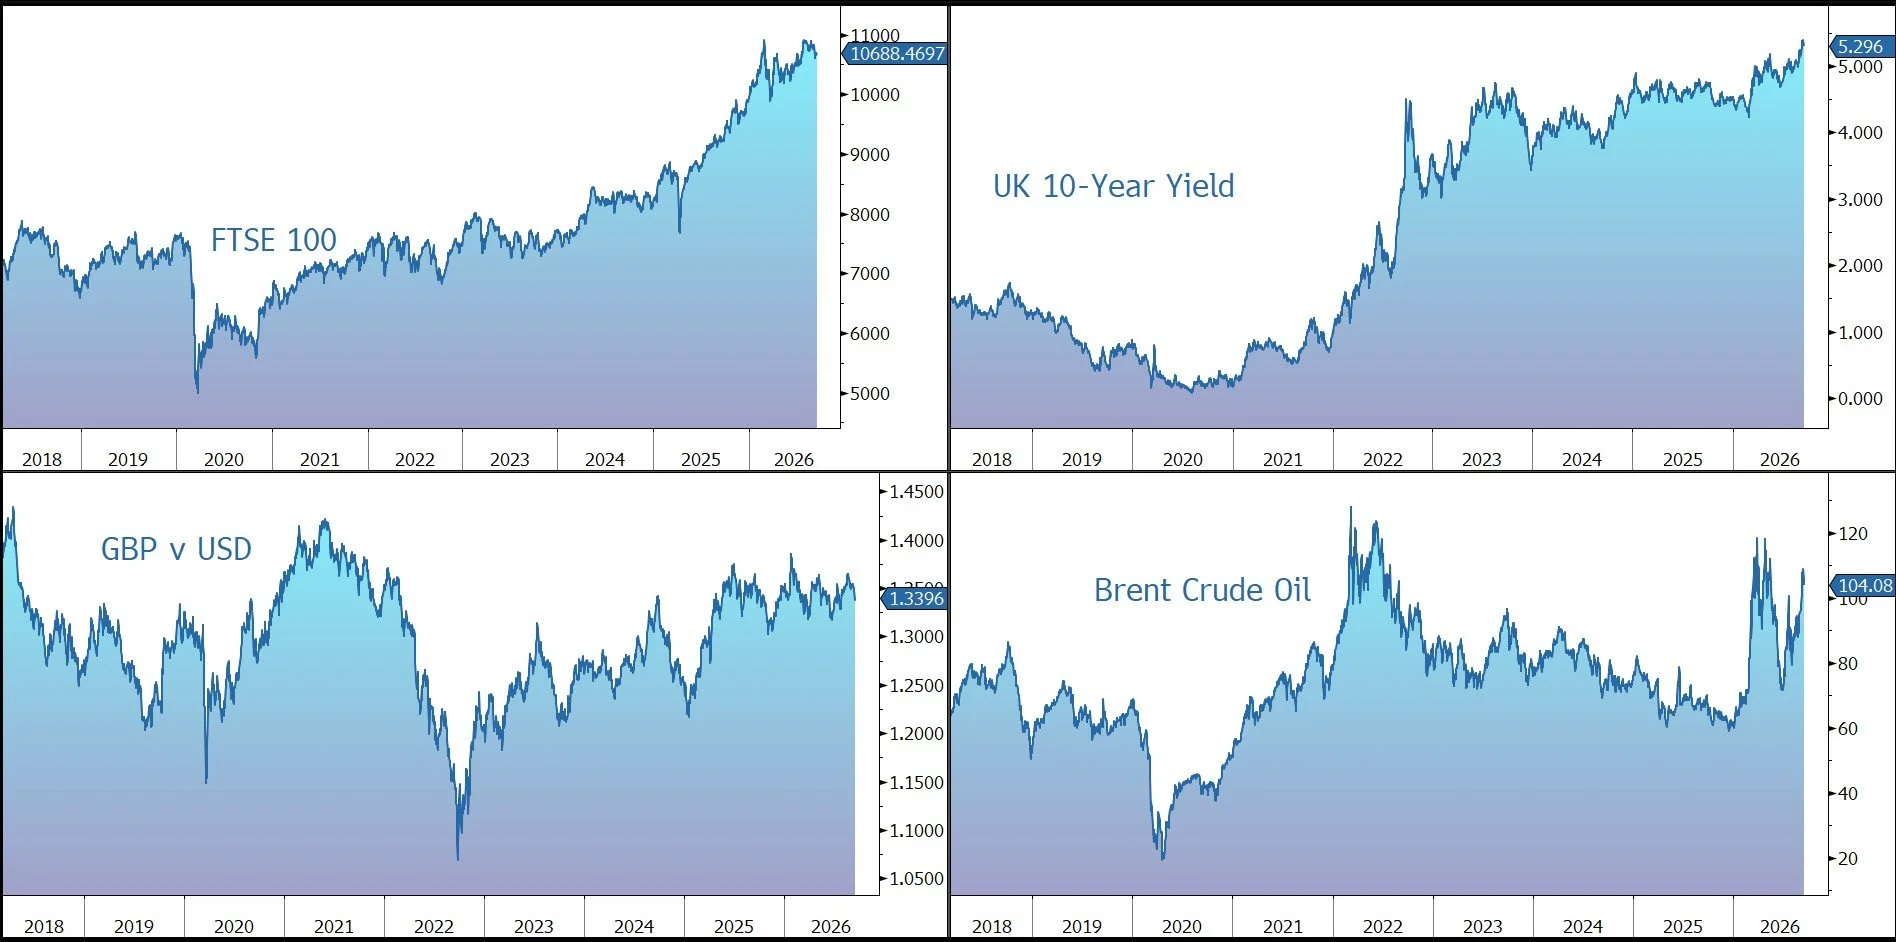
The Bank of England is expected to keep rates at 3.75% at midday today, with policymakers likely favouring a hold to focus on upside risks. However, Gilts remain under pressure – the 10-year is yielding 5.3% – given that UK August inflation came in above the BoE’s own estimate and the Fed has now moved. Sterling currently trades at $1.3395 and €1.1670.
Donald Trump threatened “very serious” EU tariffs or curbs on trade if Europe’s push to make Canada an associate member is deemed a “hostile act.” Meanwhile, Congress approved a bill giving the president new powers to slap tariffs on Russian oil buyers, potentially hitting China and India.
Brent crude fell to $104 a barrel, sliding for the second straight session following reports that Saudi Arabia plans to restore roughly half the capacity of its East-West pipeline within days and bring it back to full operation within six weeks. In the meantime, Saudi Arabia has stepped up efforts to transport more crude through the Strait of Hormuz with assistance from the US military. Reports suggest President Trump could meet Gulf leaders as soon as next week, raising hopes for some easing of tensions.
US equities fell during normal trading hours last night – S&P 500 (-0.5%); Nasdaq (-0.1%) – but rallied in the after-market following the Fed Chair’s reassuring speech. The S&P Futures are currently predicting a 0.8% increase at the open this afternoon.
In Asia this morning, markets were mixed: Nikkei 225 (+0.3%); Hang Seng (-0.7%); Shanghai Composite (-0.4%); Kospi (flat). Hong Kong property stocks fell 2% after Hong Kong followed the Fed with its own rate increase. The FTSE 100 is currently 0.9% higher at 10,784, with Next up 2% following an upgrade of its profit guidance.
Source: Bloomberg
